This analyst just slashed his price target on Byrna Technologies

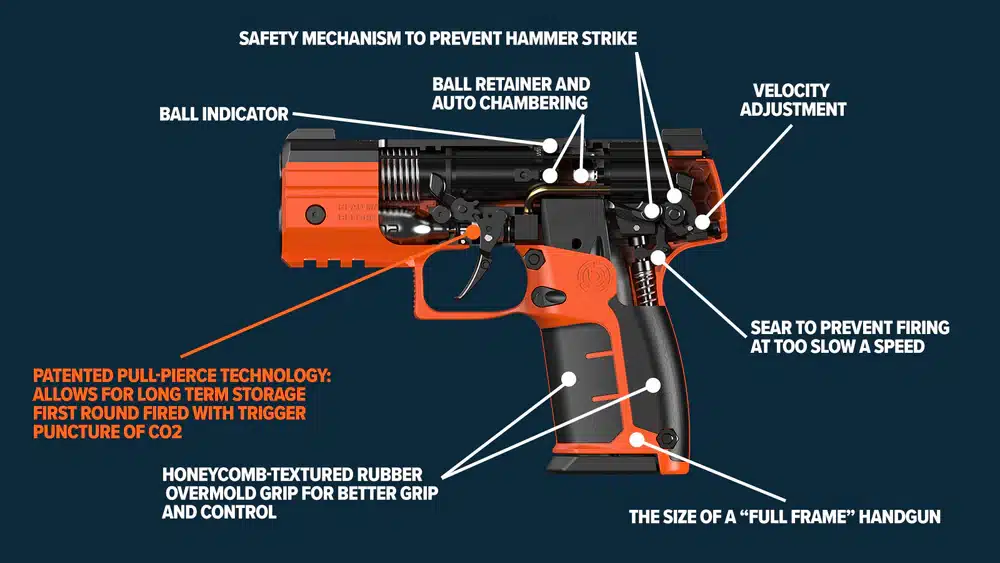
Roth Capital Markets analyst Matt Koranda maintained his “Buy” rating on Byrna Technologies (Byrna Technologies Stock Quote, Chart, News, Analysts, Financials NASDAQ:BYRN) but cut his price target to $12.50 from $26.00, saying fiscal 2026 is shaping up as a transition year under new CEO Conn Davis.
In his April 9 analysis, Koranda said first-quarter revenue matched the company’s earlier preannouncement, but profit came in light as margins were pressured by weaker mix, including lower-margin launcher sales, e-commerce trade-downs and pressure in the wholesale channel.
“As a result, we’re resetting our forecast, but acknowledge we are still counting on a successful pivot leading to renewed growth/margin expansion by 4FQ26,” he said.
Byrna reported first-quarter revenue of $29.0-million, up 11% year over year, with Adjusted EBITDA of $2.2-million and EPS of $0.03. That compared with Roth estimates of $29.0-million, $2.8-million and $0.04, and consensus forecasts of $29.5-million, $3.4-million and $0.08. Wholesale revenue rose 70% to $10.7-million, while direct-to-consumer revenue fell nine per cent to $18.1-million.
Koranda said the weakness in direct sales appears tied to lower website conversion despite rising traffic, suggesting Byrna is attracting lower-propensity shoppers who are less responsive to its higher-priced launchers. He also pointed to average order value pressure as consumers trade down into lower-priced products
“It appears that Byrna is driving lower-propensity consumers to the site that are not effectively seeing the benefits of higher-ASP launchers,” he said.
Management indicated the second quarter is tracking below expectations, and Koranda now believes sales are likely to decline year over year in both the second and third quarters as the company retools its marketing and website messaging to appeal to a broader personal safety customer base rather than a more firearms-oriented audience. He said management is targeting improvement later in fiscal 2026, with a potential return to growth in the second half and better gross margins as product mix shifts.
Koranda cut his fiscal 2026 forecast to revenue of $118.0-million and Adjusted EBITDA of $8.6-million from prior estimates of $134.0-million and $19.5-million. For fiscal 2027, he now expects revenue of $129.3-million and Adjusted EBITDA of $12.8-million, down from prior forecasts of $153.0-million and $22.9-million.
The analyst said the near-term reset will likely take several quarters to play out, though his model still gives Byrna credit for continued wholesale growth and a more stable business by late fiscal 2026.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Roth Capital Partners analyst Matt Koranda says Byrna Technologies’ (Byrna Technologies Stock Quote, Chart, News, Analysts, Financials NASDAQ:BYRN) shift toward...