This analyst is bullish on Quarterhill

Beacon Securities analyst Gabriel Leung says Quarterhill (Quarterhill Stock Quote, Chart, News, Analysts, Financials TSX:QTRH) is positioned for a re-rating after several years of restructuring and ahead of its planned acquisition of Conduent’s tolling business.
In a Sept. 3 initiation report, Leung launched coverage of Quarterhill with a “Buy” rating and $5.50 target. His target is based on 11 times his calendar 2028 EV/EBITDA estimate and assumes the Conduent deal closes around the end of 2026.
“We believe Quarterhill has reached an important point in its evolution and is poised for a significant re-rating of its stock price and valuation,” Leung said.
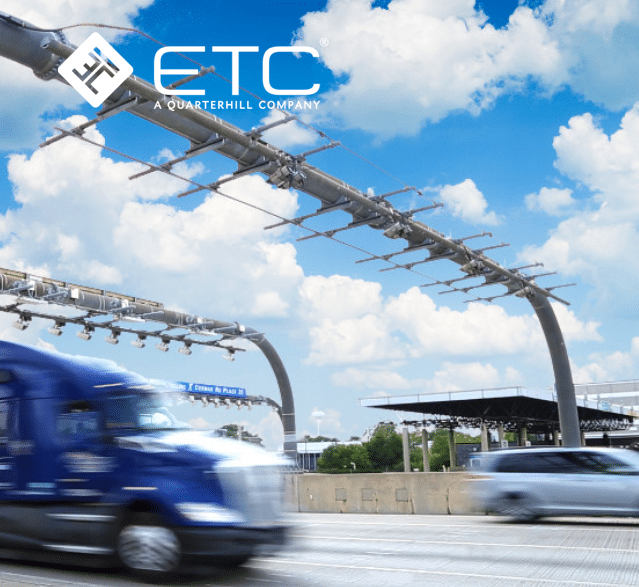
Quarterhill provides technology systems for road and transportation infrastructure, with a focus on tolling, commercial vehicle safety and enforcement.
The company serves government transportation and tolling agencies, departments of transportation, traffic engineering operators and private transportation customers, mainly in the United States.
Leung said Quarterhill’s restructuring has improved its growth and profitability profile, while new R&D investment, including AI, could increase automation and shift more revenue toward software and recurring sales.
In June, Quarterhill agreed to acquire the tolling solutions business of Conduent Business Services. Leung said the transaction would be transformational, increasing Quarterhill’s revenue base to more than $400-million from about $160-million and backlog to about $2-billion from $415-million.
He said the combined company would become the second-largest tolling platform in the United States behind TransCore, with broader capabilities in electronic tolling, back-office operations and roadside systems.
Leung said the deal should also create cross-selling opportunities because Conduent’s tolling business does not include commercial vehicle and enforcement solutions.
Quarterhill will pay $70-million in cash and issue shares representing 7% of its outstanding shares at closing. Leung estimates the transaction value at about $88-million, or roughly 0.4 times his estimated revenue for the Conduent business.
The analyst said integration is the main risk, but management’s recent track record gives him confidence in the deal.
Leung also said Quarterhill could expand internationally through acquisitions, with a potential M&A pipeline of about $3-billion. About 10% of revenue currently comes from outside North America.
He expects Quarterhill to generate Adjusted EBITDA of $14.9-million on revenue of $163.2-million in fiscal 2026, improving to Adjusted EBITDA of $41.0-million on revenue of $401.0-million in fiscal 2027.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
In his Sept. 24 update Beacon Securities analyst Gabriel Leung said Quarterhill’s (Quarterhill Stock Quote, Chart, News, Analysts, Financials TSX:QTRH)...
Roth Capital Partners analyst Scott Searle says Quarterhill (Quarterhill Stock Quote, Chart, News, Analysts, Financials TSX:QTRH) is positioned to return...