Three Canadian stocks with exposure to the data centre buildout

The rising cost of AI data centres could create opportunities well beyond the companies supplying processors, according to InvestorPlace senior investment analyst Luke Lango.
In an October article, Lango cited Bloomberg Intelligence estimates putting the global data centre market at approximately US$1.7-trillion in 2027. That was roughly 70% above its earlier estimate, despite projected capacity increasing only about 10%.
The difference reflects increasingly equipment-intensive facilities, requiring more memory, storage, networking, electrical infrastructure and cooling.
Lango favours suppliers, arguing that they can earn revenue as facilities are built, while operators must finance projects, attract customers and generate returns on their capacity.
Three Canadian stocks illustrate those different exposures. Hammond Power Solutions supplies electrical equipment, Celestica provides networking hardware, and Carrier Connect Data Solutions operates data centre facilities. Their opportunities share a spending theme, but their risks differ: manufacturing capacity and order conversion matter for suppliers, while filling available capacity is central to the operator’s outlook.
Hammond Power Solutions
National Bank Financial analyst Baltej Sidhu raised his target on Hammond Power Solutions (Hammond Power Solutions Stock Quote, Chart, News, Analysts, Financials TSX:HPS.A) to $380.00 from $355.00 on Oct. 13, maintaining his “Outperform” rating after touring its Monterrey, Mexico, facility.
As reported by The Globe and Mail, Sidhu said the visit strengthened his confidence in Hammond’s ability to expand production and capitalize on sustained infrastructure investment.
The analyst estimated Hammond’s revenue capacity at approximately $1.4-billion, excluding its recently acquired AEG business. Its Fort Worth expansion and efficiency initiatives are expected to push capacity above $1.7-billion, supporting roughly double 2025 adjusted EBITDA before any contribution from AEG.
Continued backlog growth and conversion remain the key share-price catalysts. Sidhu cautioned that slower orders or a sequential backlog decline could weigh on the stock, even if caused by timing or increased throughput.
“We believe the underlying trajectory remains positive as capacity scales and orders convert into revenue,” he said.
Celestica
TD Cowen analyst John Shao maintained his “Buy” rating and US$430.00 target on Celestica (Celestica Stock Quote, Chart, News, Analysts, Financials NYSE:CLS) in the firm’s September Canada Best Ideas report, arguing that AI infrastructure demand could prove more durable than investors expect.
Shao sees the networking buildout creating recurring demand as operators replace existing equipment with faster systems. His framework suggests Ethernet replacement activity alone could support approximately US$20-billion in annual revenue beyond 2030, with additional opportunities in servers and storage.
“Long-term demand visibility remains the key investor debate,” Shao said.
He identified OpenAI and AMD as potential growth drivers beginning in fiscal 2027, alongside continued demand for Google’s custom accelerators.
Shao forecast adjusted EBITDA of US$1.91-billion on revenue of US$20.90-billion in fiscal 2026, rising to US$3.52-billion and US$36.41-billion, respectively, in fiscal 2027. He argued that Celestica’s growth and margins justify a premium to electronics manufacturing services peers.
Carrier Connect Data Solutions
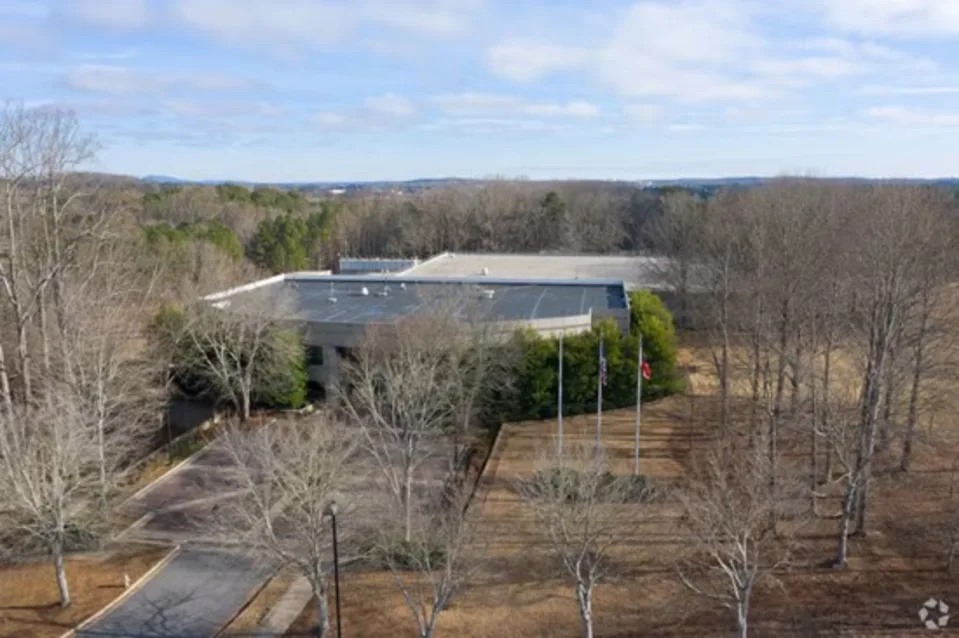
Beacon Securities analyst Gabriel Leung reiterated his “Buy” rating and $3 target on Carrier Connect Data Solutions (Carrier Connect Data Solutions Stock Quote, Chart, News, Analysts, Financials TSXV:CCDS in an Oct. 15 update following a Georgia data centre lease that increases its power capacity by 52%.
The four-megawatt Alpharetta facility brings capacity under management to 11.7 megawatts. Leung estimated that full utilization by AI computing customers could generate approximately $16.5-million in annual recurring revenue, compared with $5-million to $6-million across existing operations.
The property’s historical utility supply offers a potential expansion to 10 megawatts, subject to customer demand and utility requirements. At that capacity, Leung estimated annual recurring revenue could reach approximately $42-million.
Those estimates depend on securing customers. Leung maintained his forecasts pending further announcements, projecting fiscal 2026 revenue of $2.7-million and an adjusted EBITDA loss of $1.1-million, improving to revenue of $5.5-million and positive adjusted EBITDA of $100,000 in fiscal 2027.
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Beacon Securities analyst Gabriel Leung reiterated his “Buy” rating and $3.00 target on Carrier Connect Data Solutions (Carrier Connect Data...
Beacon Securities analyst Gabriel Leung says Carrier Connect Data Solutions’ (Carrier Connect Data Solutions Stock Quote, Chart, News, Analysts, Financials...