Itron is an undervalued stock, this analyst says

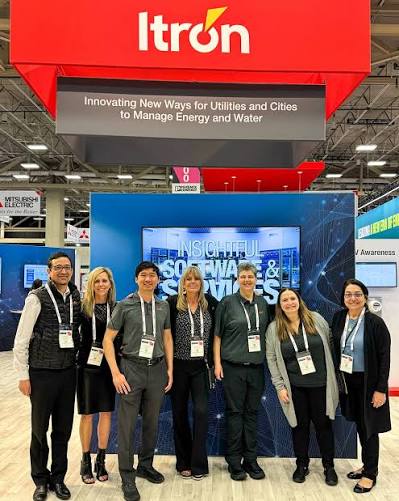
Roth Capital Partners analyst Chip Moore reiterated his “Buy” rating and US$136.00 target on Itron (Itron Stock Quote, Chart, News, Analysts, Financials NASDAQ:ITRI) ahead of its third-quarter results, citing strong demand for grid modernization and improving long-term growth prospects.
In an Oct. 20 preview, Moore said Itron’s backlog, expanding sales pipeline and shift toward an asset-light business model support his positive outlook despite slower near-term revenue growth.
“We continue to favor robust backlog and pipeline visibility and what we expect to be extended market tailwinds from underlying grid dynamics and product cycles underway,” Moore said.
“While revenue growth is more subdued near term (driven by complex projects and timing dynamics), we expect benefits of the company’s asset-light transition to drive improving wallet share, margins, and sentiment.”
Itron, which provides smart meters, grid management technology and software to utilities, is scheduled to report Q3 results before markets open on Oct. 27.
Moore forecasts revenue of US$593-million, Adjusted EBITDA of US$88.8-million and adjusted EPS of US$1.53, compared with consensus estimates of US$595.5-million, US$94.8-million and US$1.56, respectively.
The analyst said Itron is benefiting from investment in electrical grid modernization, with opportunities emerging in California, the northeastern United States and the Midwest.
Moore also expects a stronger investment cycle in natural gas distribution infrastructure over the next three to five years.
Demand is being supported by aging utility infrastructure, increasingly complex electricity networks and technology designed to improve reliability and reduce outages.
Moore highlighted Itron’s new Advanced Grid Reliability products, which help utilities identify problems earlier and restore power more quickly.
Annual recurring revenue reached US$417.0-million in Q2, up 21% year-over-year, while backlog stood at US$4.41-billion.
Moore said about 25% of the backlog is tied to higher-margin, outcomes-based solutions, a share he expects to increase.
The analyst also argued that Itron’s acquisitions of Urbint and Locusview are progressing well, with both already contributing to Adjusted EBITDA and expected to be accretive to EPS by the end of fiscal 2027.
Moore said Itron’s improving product mix and structural cost reductions should support margin expansion as revenue growth accelerates. He highlighted the stock’s valuation at less than 11 times his fiscal 2027 EV/Adjusted EBITDA estimate and about 12 times adjusted earnings.
His $136.00 target is based on approximately 20 times his fiscal 2027 adjusted EPS estimate of US$6.82.
Moore expects Itron to generate Adjusted EBITDA of US$379.4-million on revenue of US$2.37-billion in fiscal 2026, improving to Adjusted EBITDA of US$415.3-million on revenue of US$2.54-billion in fiscal 2027.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.