This analyst just raised his price target on Cematrix

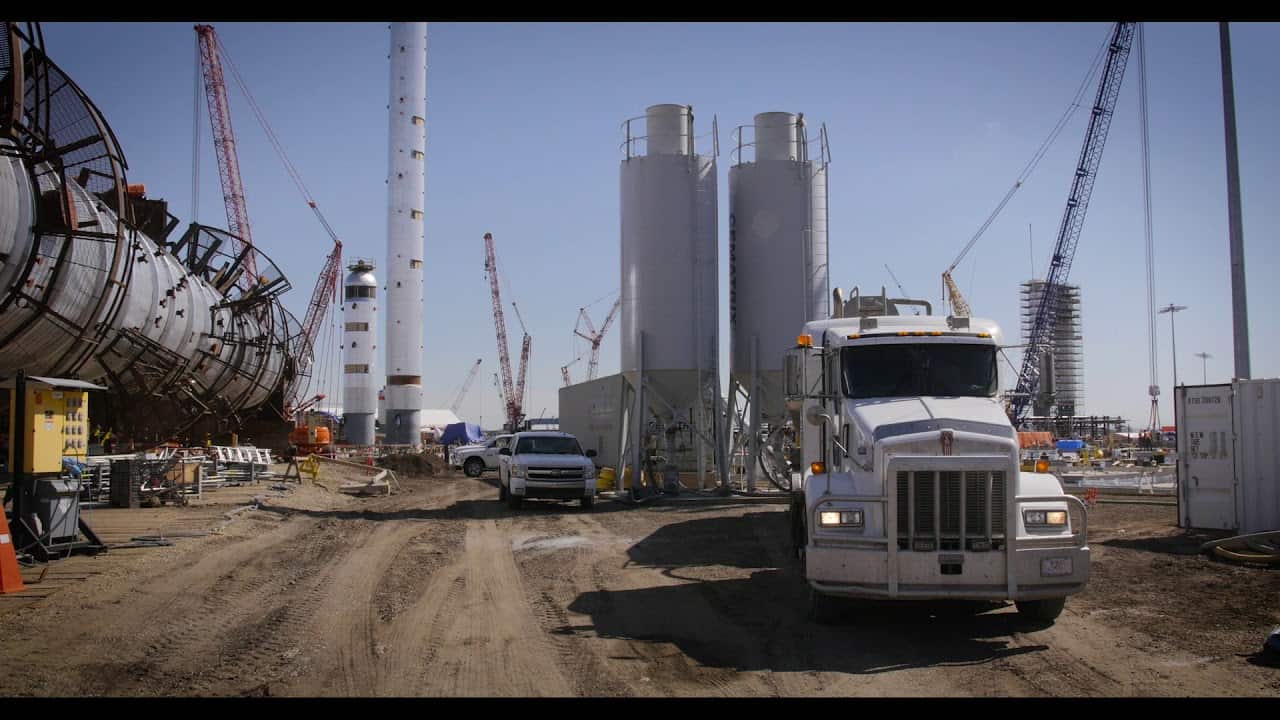
Beacon Securities analyst Russell Stanley says Cematrix’s (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) Q2 results were well ahead of expectations and showed the company’s operating leverage.
In a July 30 update, Stanley maintained his “Buy” rating on Cematrix and raised his target to $0.85 from $0.75.
“CEMX reported Q2 results that were significantly stronger than expected,” Stanley said. “While our F2026 estimate revisions are minor, we nonetheless view the Q2 results very positively, as they demonstrate the operating leverage and cash flow generation capabilities of this business.”
Cematrix reported Q2 revenue of $18.7-million and Adjusted EBITDA of $5.0-million, ahead of Stanley’s estimates of $11.0-million and $1.3-million. Revenue beat his forecast by 70%, while Adjusted EBITDA was almost four times his estimate.
Stanley said Q2 is typically a ramp-up quarter, with Q3 and Q4 usually the strongest periods for construction activity. Management said Q2 benefited from two large projects or scopes of work that started and finished during the quarter.
Gross margin beat Stanley’s forecast by 698 basis points, which he attributed mainly to scale economies on the stronger revenue. SG&A was also lower than expected, helping lift Adjusted EBITDA margin to 27%.
Operating cash flow before working capital was $4.8-million, also about four times Stanley’s forecast. Cematrix ended the quarter with $16.2-million in cash, $900,000 of debt and $2.2-million of leases.
Stanley said the company’s modest capital spending profile means strong operating cash flow is translating into solid free cash flow. Cematrix also has an unused $8.0-million revolver with CIBC.
During Q2, Cematrix repurchased 513,000 shares at an average cost of 52 cents per share. Since launching its normal course issuer bid, the company has repurchased 1.9-million shares at an average cost of 38 cents.
Stanley said essentially all of the company’s 8.2-million warrants expired unexercised, reducing the fully diluted share count used in his valuation by about 5%. The lower share count, along with a slightly higher fiscal 2027 Adjusted EBITDA forecast on lower SG&A expectations, supported his target increase.
Backlog declined to $62-million in Q2, reflecting the strong revenue performance. Cematrix announced $9.2-million of awards in the quarter and $26.2-million in the first half.
Management said Q3 could look similar to Q3 2025, when Cematrix generated revenue of $15.3-million and Adjusted EBITDA of $3.5-million. Stanley said that would represent an unusual sequential decline, but Q2 benefited from exceptional project timing.
The stock trades at 4.5 times Stanley’s fiscal 2027 Adjusted EBITDA forecast, a 52% to 56% discount to infrastructure and cement company averages. Potential catalysts include contract wins, Q3 results and M&A activity.
The analyst expects Cematrix to generate Adjusted EBITDA of $11-million on revenue of $60-million in fiscal 2026, improving to Adjusted EBITDA of $15-million on revenue of $74-million in fiscal 2027.
-30-
Nick Waddell
Founder of Cantech Letter
Cantech Letter founder and editor Nick Waddell has lived in five Canadian provinces and is proud of his country's often overlooked contributions to the world of science and technology. Waddell takes a regular shift on the Canadian media circuit, making appearances on CTV, CBC and BNN, and contributing to publications such as Canadian Business and Business Insider.
Related Posts
Beacon Securities analyst Russell Stanley says Cematrix (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) has enough equipment capacity...
Beacon Securities analyst Russell Stanley says new contract awards add to Cematrix’s (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials...