Cematrix is cementing its future, this analyst says

Beacon Securities analyst Russell Stanley says new contract awards add to Cematrix’s (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) sales pipeline after a stronger-than-expected Q2.
In an Aug. 21 update, Stanley maintained his “Buy” rating and $0.85 target on Cematrix.
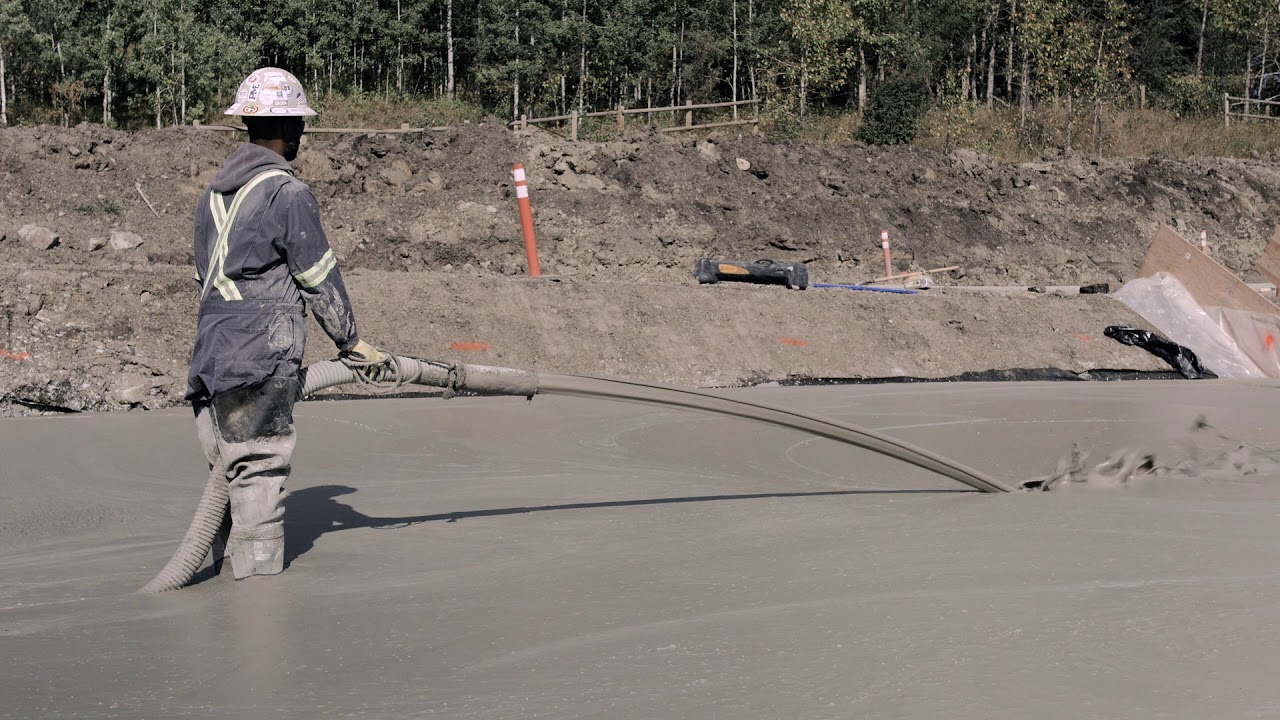
Cematrix announced $8.2-million of new contract awards, including tunnel grouting, load-reducing fill for a seawall and tank base project, and pipeline grouting work. Some of the work is expected to be completed this year, with the rest scheduled for fiscal 2027.
Stanley said management continues to see strong bidding activity and a robust sales pipeline.
The update follows Cematrix’s Q2 results, which included revenue of $18.7-million and Adjusted EBITDA of $5.0-million, well ahead of Stanley’s forecasts of $11.0-million and $1.3-million.
Revenue rose 76% year-over-year, while Adjusted EBITDA increased 107%. Backlog declined to $62-million after the strong revenue quarter.
Cematrix ended Q2 with more than $16-million of cash, modest debt and leases of $3.1-million, and an unused $8-million CIBC revolver.
Stanley said the balance sheet could support at least one acquisition.
The analyst said Cematrix trades at 4.3 times his fiscal 2027 Adjusted EBITDA forecast, a 57% to 58% discount to infrastructure and cement peers.
Potential catalysts include further contract wins, Q3 results in November and M&A activity.
Stanley expects Cematrix to generate Adjusted EBITDA of $11-million on revenue of $60-million in fiscal 2026, improving to Adjusted EBITDA of $15-million on revenue of $74-million in fiscal 2027.
-30-
Tara Whittet
Writer
Tara Whittet is Senior Sales Manager at Cantech Letter.
Related Posts
Beacon Securities analyst Russell Stanley says Cematrix (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) has enough equipment capacity...
Beacon Securities analyst Russell Stanley says Cematrix’s (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) Q2 results were well...