Is Cematrix (TSX:CEMX) a buy?

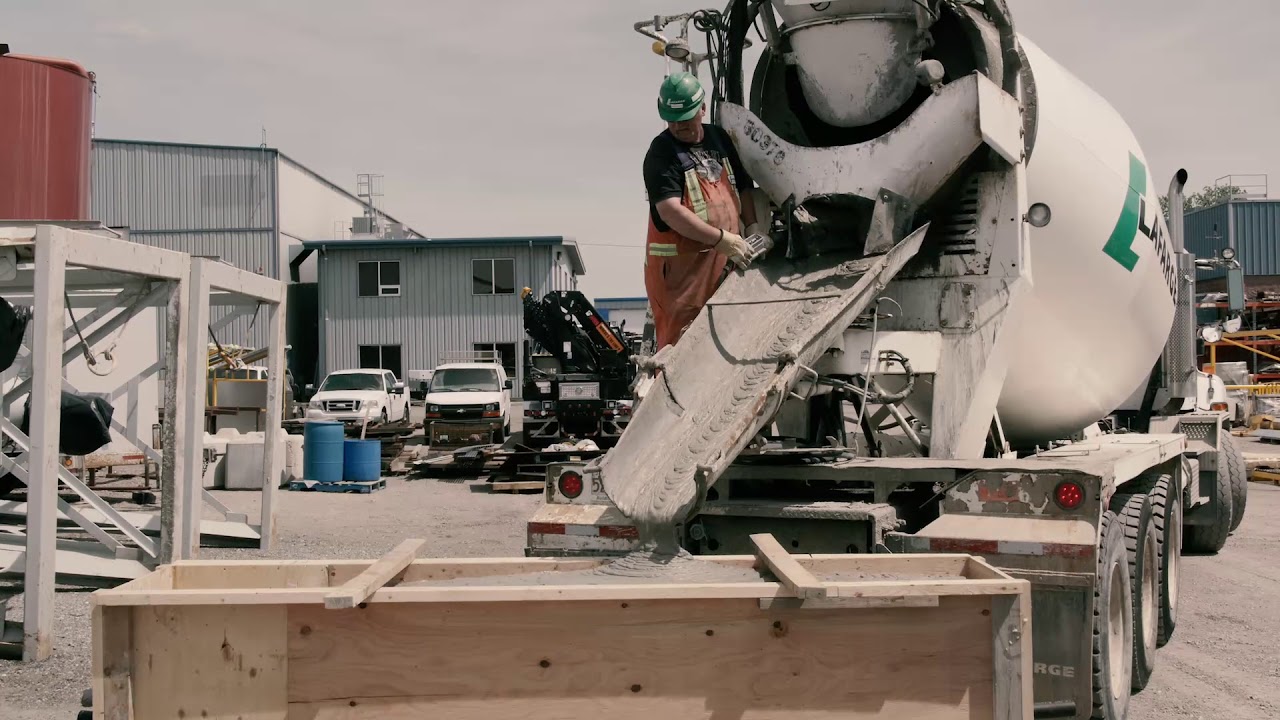
Beacon Securities analyst Russell Stanley says Cematrix (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) has enough equipment capacity to support significant organic growth without major new investment.
In a Sept. 18 update, Stanley reiterated his “Buy” rating and $0.85 target on Cematrix.
The company hosted a webinar Thursday aimed mainly at new investors. Stanley said management reiterated previously communicated plans and priorities, which he viewed favourably.
Management estimated Cematrix could double or triple revenue using its existing equipment fleet and could grow revenue by 20% to 50% with little to no headcount expansion.
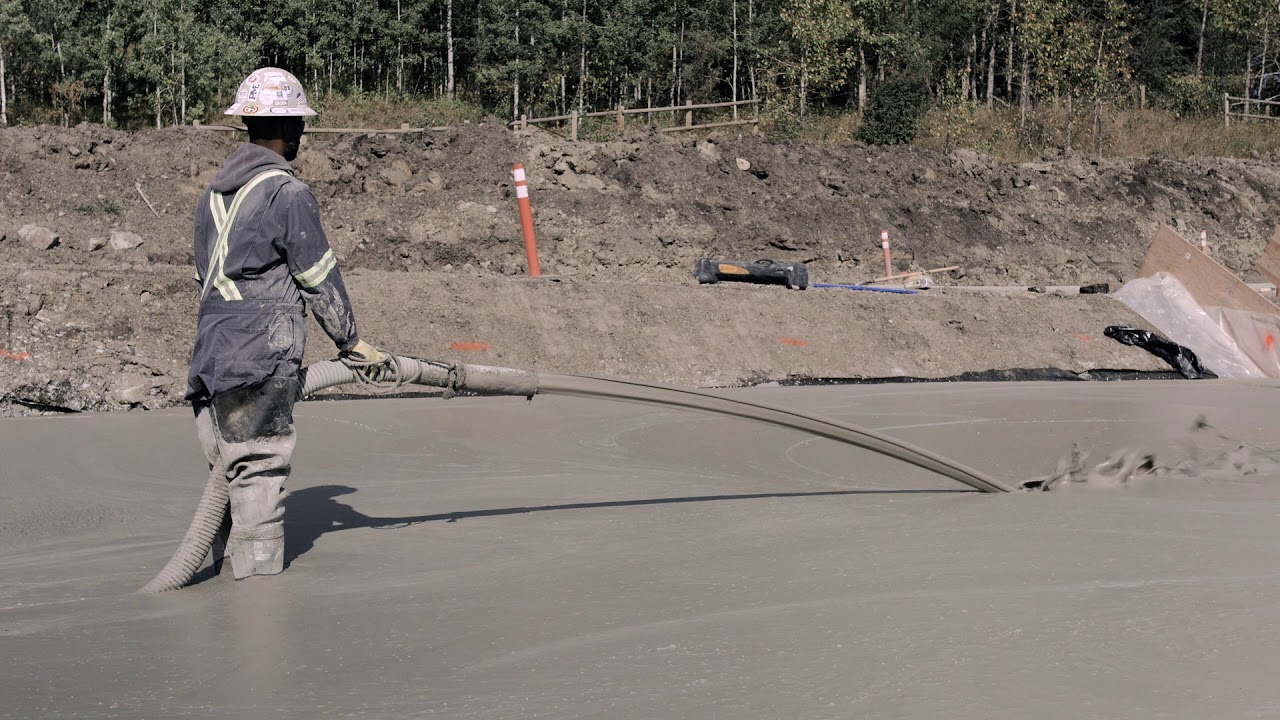
The company continues to work through a roughly US$20-million project in North Carolina, which management believes is the largest cellular concrete project in North America. Cematrix has completed two of five bridges, with work on the third expected to begin this month.
Cematrix exited Q2 with a $62-million backlog and has announced $34-million of contract wins year-to-date, including more than $8-million not reflected in the latest backlog.
Stanley said the U.S. remains the company’s stronger growth market, accounting for almost 80% of trailing-12-month revenue. Management said tariffs have not had a material impact because raw materials are sourced locally and the company operates through U.S. subsidiaries with U.S. staff.
Cematrix ended Q2 with more than $16-million in cash, about $3-million of debt and leases, and an unused $8-million revolver.
The analyst said the balance sheet gives Cematrix capacity for acquisitions. Management’s preferred target remains another pure-play cellular concrete producer with complementary geographic coverage, though selling interest has been limited.
A secondary option would be a specialty contractor with a technical sales team focused on an adjacent product, creating cross-selling opportunities.
Stanley said Cematrix trades at 4.2 times his fiscal 2027 Adjusted EBITDA estimate, a 55% to 58% discount to cement, infrastructure and engineering peers.
Potential catalysts include more contract wins, Q3 results in November and M&A activity.
Stanley expects Cematrix to generate Adjusted EBITDA of $11-million on revenue of $60-million in fiscal 2026, improving to Adjusted EBITDA of $15-million on revenue of $74-million in fiscal 2027.
-30-
Nick Waddell
Founder of Cantech Letter
Cantech Letter founder and editor Nick Waddell has lived in five Canadian provinces and is proud of his country's often overlooked contributions to the world of science and technology. Waddell takes a regular shift on the Canadian media circuit, making appearances on CTV, CBC and BNN, and contributing to publications such as Canadian Business and Business Insider.
Related Posts
Beacon Securities analyst Russell Stanley says new contract awards add to Cematrix’s (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials...
Beacon Securities analyst Russell Stanley says Cematrix’s (Cematrix Corporation Stock Quote, Chart, News, Analysts, Financials TSX:CEMX) Q2 results were well...