Analyst raises Rogers target on value of Leafs and Jays

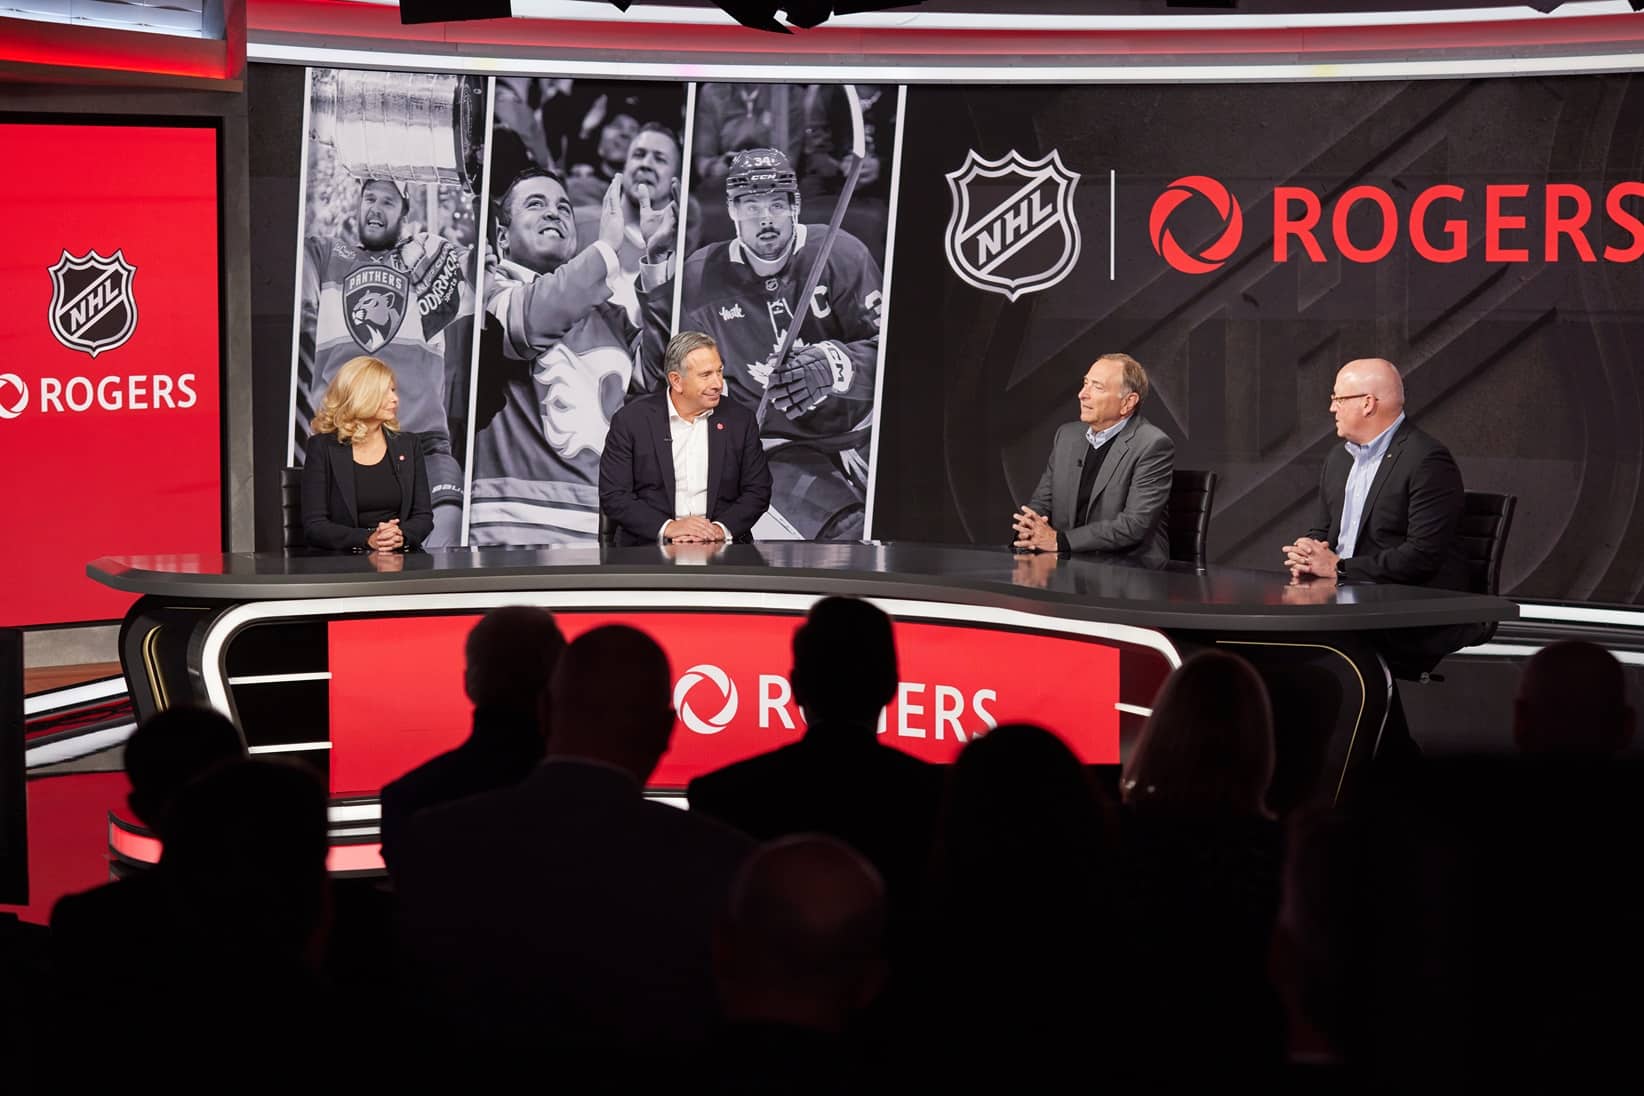
Desjardins Securities analyst Jérôme Dubreuil raised his target on Rogers Communications (Rogers Communications Stock Quote, Chart, News, Analysts, Financials TSX:RCI.B) to $57.00 from $55.00, citing the potential value unlocked through minority stake sales in the company’s professional sports holdings.
As reported by the Globe and Mail, in an Oct. 26 update, Dubreuil maintained his “Buy” rating, arguiing that the proposed monetization of Rogers’ sports assets could provide meaningful upside for shareholders. The average analyst target is $59.83.
“We currently assume RCI will sell minority stakes of 20%–30% of its sports portfolio,” Dubreuil said. “With potential sales likely occurring in 1H27, we expect the company to benefit from higher private market valuations, based on Forbes valuations, for the Toronto Maple Leafs, Toronto Blue Jays and Toronto FC.”
Dubreuil expects Rogers to sell minority interests in its sports portfolio during the first half of 2027, based on a combined valuation of approximately $25-billion.
He said recent transactions involving professional sports franchises support higher valuations, although Forbes’ latest estimate for the Toronto Raptors was somewhat disappointing. Forbes valued the Raptors at US$5.9-billion in its Oct. 16 update, up 9% from US$5.4-billion a year earlier. That compares with average NBA franchise valuation growth of 14% and Sportico’s estimate of US$6.5-billion for the Raptors.
“The valuation increase has nonetheless contributed to our higher target price,” Dubreuil said.
The analyst noted that Forbes is expected to update its NHL franchise valuations in December, potentially providing another benchmark for Rogers’ sports holdings.
Dubreuil estimates that selling minority stakes could create an additional $5 to $6 per Rogers share compared with retaining full ownership of the assets. “Sports monetization could create $5–6/share (vs keeping 100% of the assets), of which we estimate at least half is not reflected in the share price,” he said.
Beyond the sports portfolio, Dubreuil described Rogers’ third-quarter results as decent, although underlying operating metrics remained relatively weak. He said the company’s strong cash generation and management’s indication that lower capital spending as a percentage of revenue could continue into 2027.
“A key highlight of RCI’s 3Q results was its robust cash generation,” Dubreuil said. “Even using our more conservative normalized FCF definition, RCI now trades at a 2027E FCF yield above 10%, while the yield based on the company’s definition stands at approximately 17%.”
Dubreuil said Rogers’ free cash flow valuation remains attractive even before considering its sports assets.
He also believes concerns about potential competition from SpaceX are unlikely to materially affect Canada’s telecommunications market, although he acknowledged that U.S. telecom valuations can influence investor sentiment toward Canadian operators. “RCI’s FCF yield (our definition) of 10%, before assigning any value to sports, is compelling,” he said.
Dubreuil’s revised $57.00 target is based on the average of discounted cash flow and net asset value calculations. “Our valuation is based on the average of a DCF and an NAV, which yields our updated target price,” he said.
He attributed the increase to the revised Raptors valuation and lower yields, while continuing to apply a 40% discount to the estimated value of Rogers’ sports assets.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Desjardins Securities analyst Jerome Dubreuil says Rogers Communications’ (Rogers Communications Stock Quote, Chart, News, Analysts, Financials TSX:RCI.B) sports assets could...
National Bank Financial analyst Adam Shine says Rogers Communications’ (Rogers Communications Stock Quote, Chart, News, Analysts, Financials TSX:RCI.B) deal to...