Decisive Dividend Corporation is a buy, this analyst says

Beacon Securities analyst Russell Stanley maintained his “Buy” rating and $12.50 target on Decisive Dividend Corporation (Decisive Dividend Corporation Stock Quote, Chart, News, Analysts, Financials TSXV:DE),arguing its recent acquisition of a European fireplace manufacturer and potential for further acquisitions could support earnings growth and improve shareholder returns.
Stanley noted that the Kelowna, B.C.-based company’s shares have stabilized relative to competitor Exchange Income Corporation following several months of underperformance. “The stock is now performing in line with EIF after underperforming from May through September,” Stanley said on Nov. 3.
He expects Decisive to report third-quarter revenue of $39.7-million and Adjusted EBITDA of $6.4-million, compared with consensus estimates of $39.6-million and $6.8-million, respectively. The results, scheduled for release after markets close Nov. 4, will include the first full-quarter contribution from Be Fire, which Decisive acquired in June for $20-million in cash.
“This strengthened the company’s Hearth business, which is not only Decisive’s highest return vertical, but it also tends to see stronger demand during periods of energy price volatility,” Stanley wrote. “This transaction also diversified the company’s revenue base geographically by adding a platform in Continental Europe, specifically Belgium and France.”
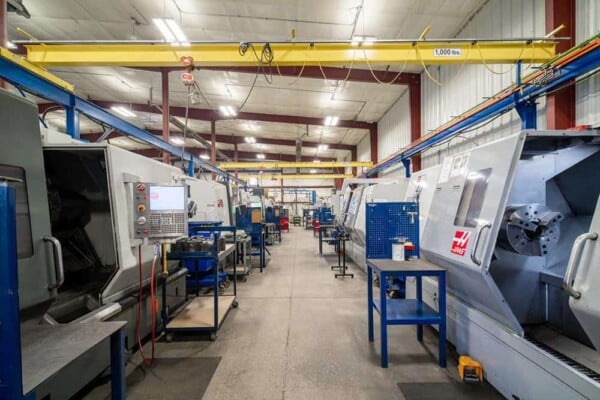
Decisive acquires and operates established manufacturing businesses, focusing on companies with recurring demand, stable cash flow and opportunities for expansion.
Stanley said the Be Fire acquisition could increase earnings from the company’s fireplace and heating products while reducing its dependence on the Canadian market.
He also expects the quarter to demonstrate improving dividend coverage. Stanley forecasts free cash flow after maintenance capital expenditures of $3.5-million, or $0.16 per share, representing a 15% increase year-over-year. That would reduce Decisive’s trailing 12-month dividend payout ratio to approximately 80% from 83% in the previous quarter, moving it closer to management’s target ceiling of 75%. The company currently pays a monthly dividend of $0.045 per share, representing an annualized yield of approximately 7%.
Stanley thinks the relatively high yield could provide valuation upside if investors become more confident in the company’s cash flow and dividend sustainability. He estimates the shares would need to increase almost 40% to $10.80 to bring the dividend yield down to 5%, its previous low in March 2024.
Stanley also expects acquisitions to remain an important part of Decisive’s growth strategy. As of late July, the company had approximately $40-million available under its $125-million revolving credit facility, along with an unused $75-million expansion option. The financing provides capacity for additional purchases without an immediate need to raise equity.
“Decisive’s sweet spot continues to be private companies producing $2-$6M in adj EBITDA,” Stanley said.
He expects management to provide an update on its acquisition pipeline during the company’s Nov. 5 conference call.
Stanley forecasts Decisive will generate Adjusted EBITDA of $27.3-million on revenue of $163.7-million in fiscal 2026, improving to Adjusted EBITDA of $38.1-million on revenue of $186.6-million in fiscal 2027.
-30-
Nick Waddell
Founder of Cantech Letter
Cantech Letter founder and editor Nick Waddell has lived in five Canadian provinces and is proud of his country's often overlooked contributions to the world of science and technology. Waddell takes a regular shift on the Canadian media circuit, making appearances on CTV, CBC and BNN, and contributing to publications such as Canadian Business and Business Insider.
Related Posts
Beacon Securities analyst Russell Stanley says Decisive Dividend’s (Decisive Dividend Corporation Stock Quote, Chart, News, Analysts, Financials TSXV:DE) acquisition of...
Beacon Securities analyst Russell Stanley maintained his “Buy” rating and $7.00 target for Decisive Dividend Corporation (Decisive Dividend Corporation Stock...