Firan wins another target raise, this time to $40.00

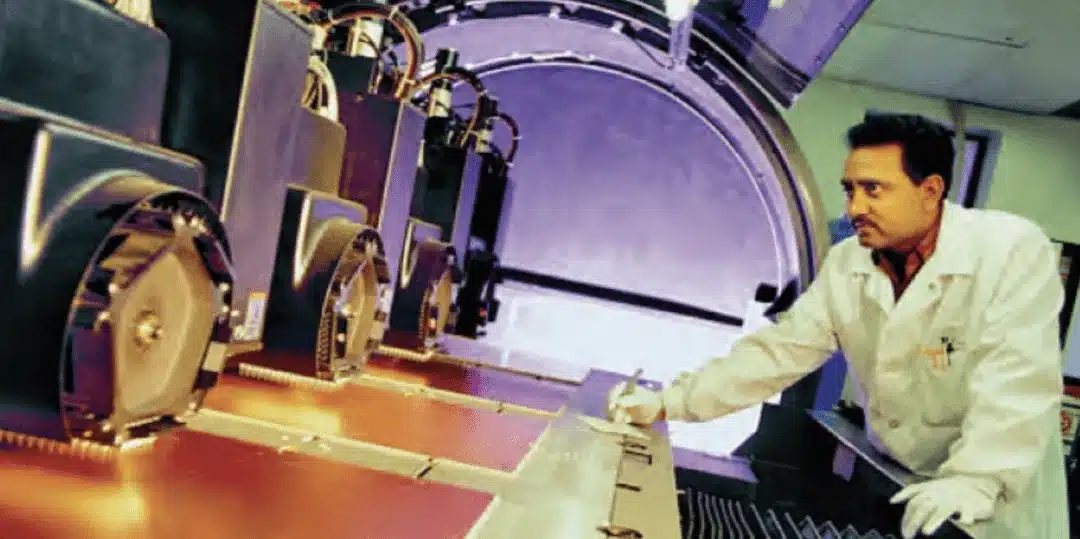
Beacon Securities analyst Russell Stanley raised his target on Firan Technology Group (Firan Technology Group Stock Quote, Chart, News, Analysts, Financials TSX:FTG) to $40.00 from $36.00, citing stronger demand from aerospace and defence customers and an improved earnings outlook.
Stanley maintained his “Buy” rating, raising his fiscal 2028 estimates and valuation multiple.
“This week has seen multiple direct customers report quarterly results and provide updated outlooks/guidance that bode well for FTG’s demand profile,” Stanley said in his Oct. 22 update.
The analyst said strong order growth and expanding backlogs among major aerospace and defence companies point to sustained demand for Firan’s products and highlighted recent results from Lockheed Martin, RTX and GE Aerospace, all of which exceeded analyst expectations and raised or improved their financial outlooks. Lockheed Martin reported a book-to-bill ratio of four times, with backlog increasing 27% year-over-year. The company also announced a framework agreement with the U.S. Department of War supporting production of 156 F-35 fighter jets annually over 10 years.
Stanley said Firan has supplied printed circuit boards for the F-35 program for approximately a decade. He said the agreement provides greater visibility for Lockheed Martin and its suppliers to invest in additional production capacity.
RTX reported a book-to-bill ratio of 3.2 times, with backlog increasing 36% year-over-year. It also raised its fiscal 2026 revenue growth guidance to 10% to 11% from 8% to 9%. GE Aerospace raised its fiscal 2026 revenue growth outlook to 19% to 20% from a previous forecast in the high teens.
Stanley said the results reinforce his expectation that aerospace and defence manufacturers will continue increasing capital spending. “Framework agreements such as the one LMT announced this morning are intended to give prime contractors and their suppliers (like FTG) the visibility to materially increase production capacity,” he said.
Lockheed Martin, RTX and Northrop Grumman reiterated capital spending plans implying weighted average growth of 25% in 2026, followed by another 14% in 2027. That compares with a compound annual growth rate of about 3% between 2021 and 2025.
Stanley also pointed to results from Firan competitor TTM Technologies, which exceeded expectations but saw its shares fall sharply amid concerns about its data centre revenue mix. He said TTM’s data centre and networking business accounted for 41% of quarterly revenue, below management’s earlier expectations.
“Data Center/Networking revenue has supplanted Aerospace & Defense (A&D) as TTMI’s #1 revenue contributor, whereas FTG continues to be an A&D pureplay, which we believe gives it stronger visibility,” he added.
Following the customer updates, Stanley increased his fiscal 2028 Adjusted EBITDA forecast to slightly more than $65-million from just under $63-million. He said the revised earnings outlook accounts for $2 of his target increase, with a higher valuation multiple contributing another $2. Firan now trades at approximately 13.6 times his fiscal 2028 EV/Adjusted EBITDA estimate.
Stanley expects Firan to generate Adjusted EBITDA of $51-million on revenue of $251-million in fiscal 2027, improving to Adjusted EBITDA of $65-million on revenue of $280-million in fiscal 2028.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Government drone orders and classified defence programs are supporting the growth outlooks for Volatus Aerospace (Volatus Aerospace Stock Quote, Chart,...
Beacon Securities analyst Russell Stanley raised his target on Firan Technology Group (Firan Technology Group Stock Quote, Chart, News, Analysts,...