Atlas Engineered Products: Buy, Sell or Hold?

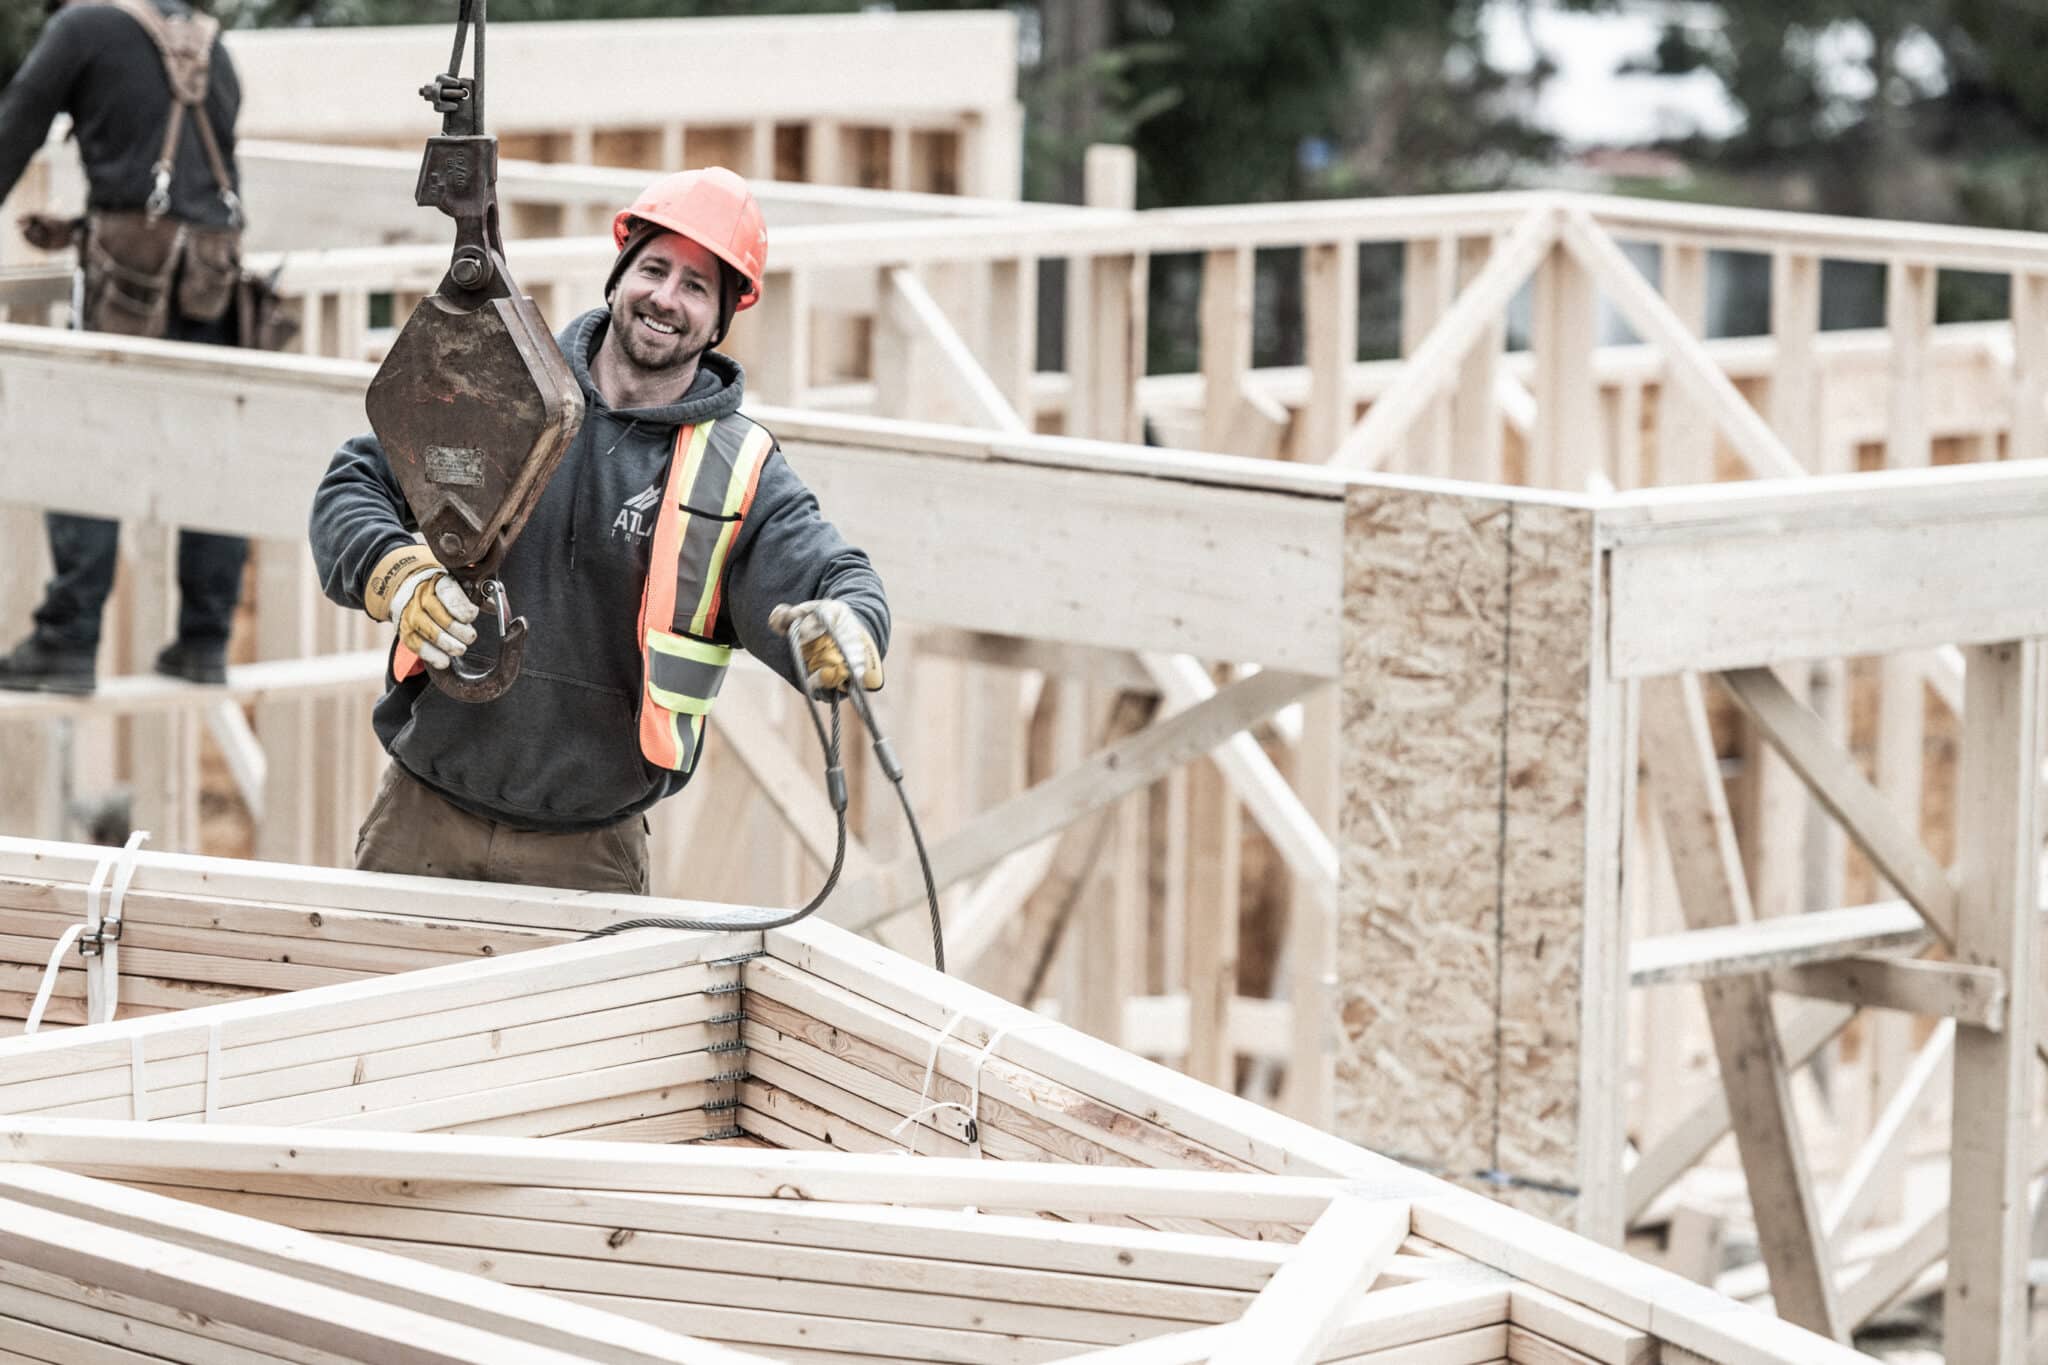
Beacon Securities analyst Russell Stanley reiterated his “Buy” rating and $1.00 target on Atlas Engineered Products (Atlas Engineered Products Stock Quote, Chart, News, Analysts, Financials TSXV:AEP) following a visit to the company’s new robotic roof truss manufacturing facility in Clinton, Ontario.
Stanley said the facility could significantly improve productivity and serve as a model for future expansion.
“We toured Atlas’ new robotic truss manufacturing facility in Clinton, Ontario, and came away impressed by the level of automation and the expansion potential,” Stanley said in his Oct. 22 report. “The associated productivity improvement should enable AEP to continue building market share, and we expect this facility to be the template for additional robotic manufacturing sites in Canada.”
Headquartered in Nanaimo, B.C., Atlas manufactures engineered roof trusses, floor trusses and wall panels for residential and commercial construction. The company recently completed commissioning of the Clinton facility and has begun producing roof trusses for sale.
Stanley pointed out that the approximately $20-million investment was funded primarily through a $15-million equity financing completed in June 2024, along with $4-million in federal government support. Of the federal funding, $3.6-million was received during Q2.
“We view that federal support favourably as it represents further confirmation that the federal government is taking concrete action to support housing construction, and because the funding is evidence that AEP is on the government’s radar as a company positioned to help solve affordability pain,” Stanley said.
The analyst said there are obvious productivity gains from automation. The new 42,000-square-foot facility currently operates one production line on a single shift, requiring just two employees. Stanley said it can already produce roof trusses at the same pace as the adjacent traditional manufacturing facility, which requires 12 employees. He estimates adding a second robotic line and moving to continuous production could increase output sixfold while requiring a total of 12 employees.
The existing conventional facility will continue operating alongside the robotic plant. Stanley said the improved productivity could help Atlas address two major challenges facing homebuilders: onsite labour costs and construction timelines.
Prefabricated trusses reduce the labour required at construction sites and can accelerate completion of the building exterior, allowing builders to reach financing milestones sooner.
Looking ahead, Stanley expects Atlas to report Q3 results in late November. He forecasts revenue of $22.3-million and Adjusted EBITDA of $3.5-million, compared with consensus estimates of $22.5-million and $2.3-million, respectively. However, he does not expect meaningful revenue from the robotic facility until Q4, since commissioning was completed after the third quarter ended.
Stanley also highlighted Atlas’s valuation, with shares trading at five times his fiscal 2027 EV/Adjusted EBITDA estimate, representing a 50% discount to U.S. peer Builders FirstSource.
Stanley expects Atlas to generate Adjusted EBITDA of $7.6-million on revenue of $69.1-million in fiscal 2026, improving to Adjusted EBITDA of $13.4-million on revenue of $82.2-million in fiscal 2027.
-30-
Nick Waddell
Founder of Cantech Letter
Cantech Letter founder and editor Nick Waddell has lived in five Canadian provinces and is proud of his country's often overlooked contributions to the world of science and technology. Waddell takes a regular shift on the Canadian media circuit, making appearances on CTV, CBC and BNN, and contributing to publications such as Canadian Business and Business Insider.
Related Posts
Beacon Securities says Atlas Engineered Products’ (Atlas Engineered Products Stock Quote, Chart, News, Analysts, Financials TSXV:AEP) Q2 results should show...
Beacon Securities analyst Russell Stanley maintained a “Buy” rating and $1.50 target for Atlas Engineered Products (Atlas Engineered Products Stock...