AZZ stock is a buy, this analyst says

Roth Capital Partners analyst Gerry Sweeney maintained his “Buy” rating and US$170.00 target on AZZ (AZZ Stock Quote, Chart, News, Analysts, Financials NYSE:AZZ) following stronger-than-expected fiscal Q2 results and increased full-year guidance.
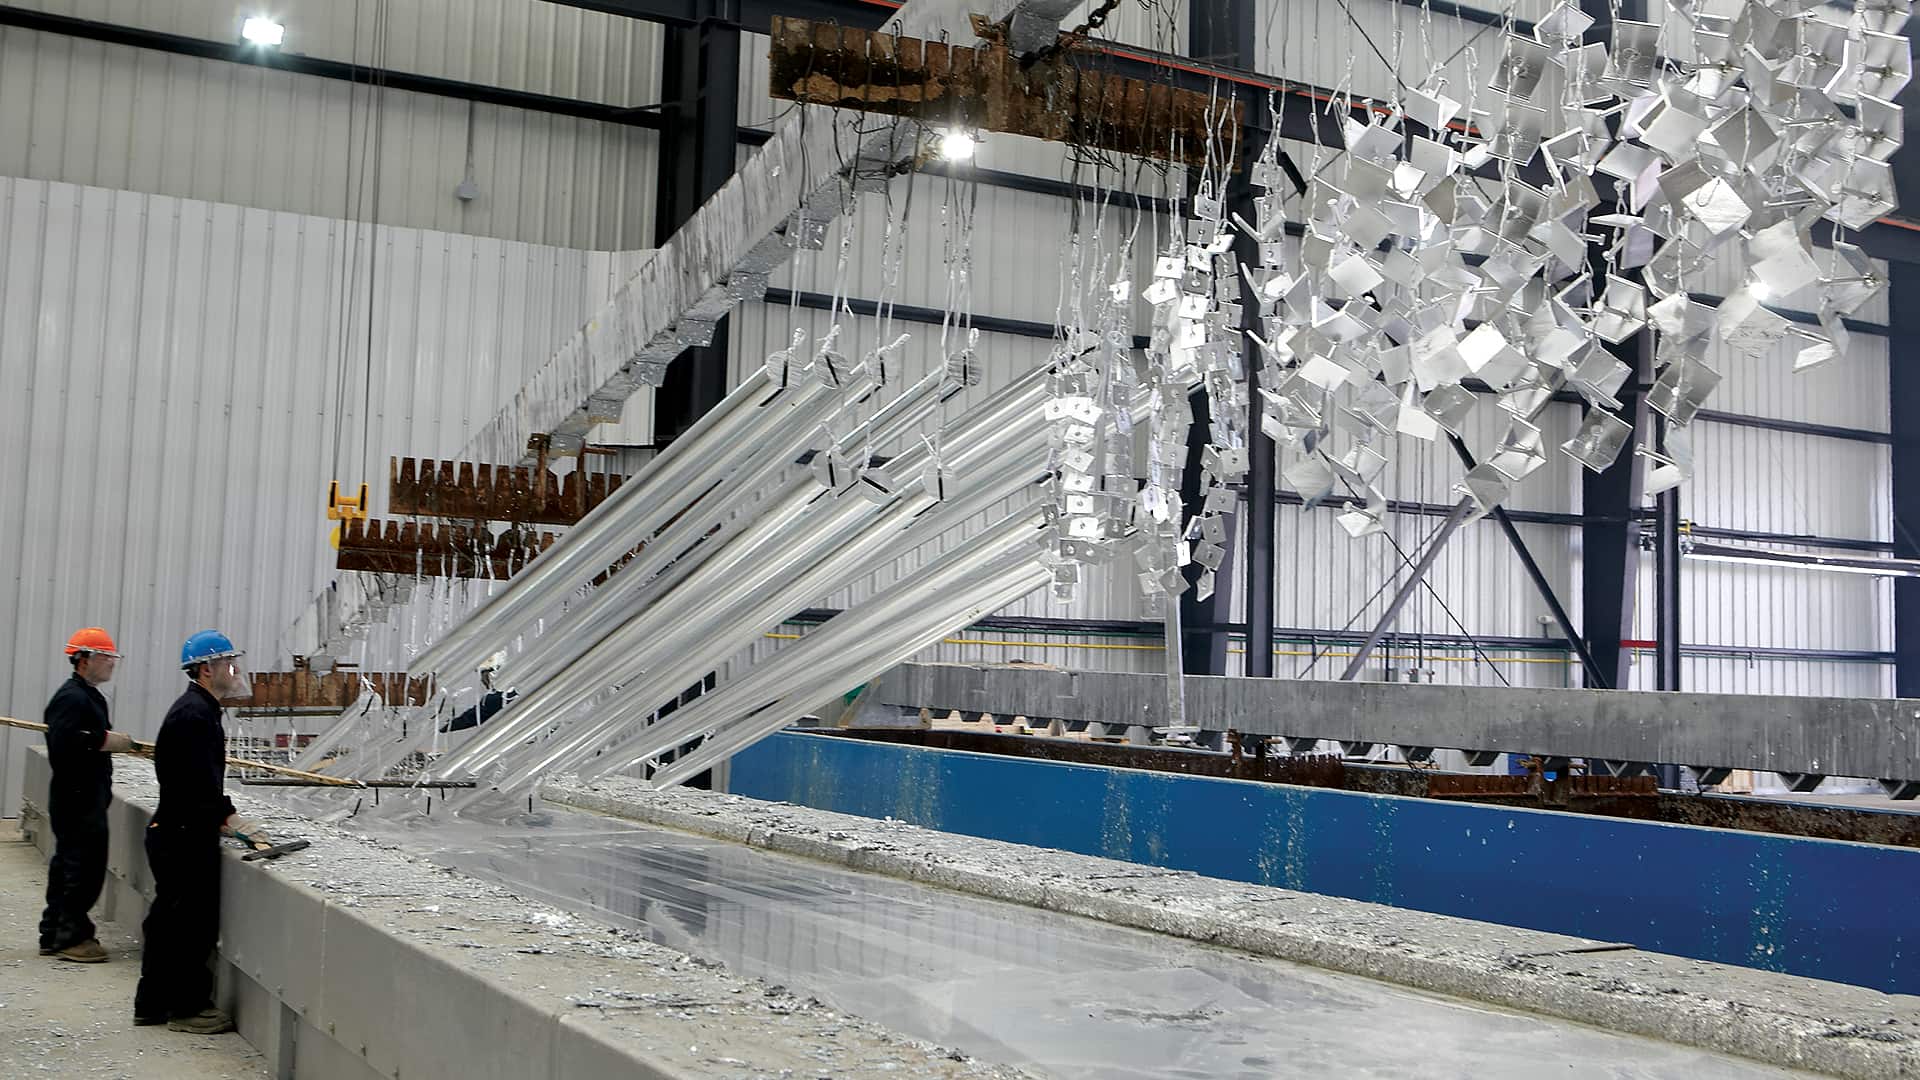
In his Oct. 16 update, Sweeney said AZZ’s Metal Coatings business continues to benefit from strong demand across construction, industrial, infrastructure and transportation markets.
AZZ reported fiscal Q2 2027 revenue of US$486.9-million, Adjusted EBITDA of US$110.9-million and adjusted EPS of US$2.00, ahead of Sweeney’s estimates of US$461.2-million, US$102.0-million and US$1.79, respectively.
Metal Coatings revenue rose 22.9% year-over-year to US$233.5-million, supported by higher volumes and pricing. Adjusted EBITDA reached US$71.6-million, with margins of 30.7%.
Precoat Metals revenue rose 11.5% to US$253.4-million, while Adjusted EBITDA reached US$53.8-million. Margins improved 100 basis points to 21.2%, helped by higher volumes, pricing and increased production at AZZ’s Washington, Missouri facility.
Sweeney believes the Washington facility remains on track to reach targeted utilization by fiscal year-end, with about 75% of capacity already allocated.
The analyst said AZZ is pursuing growth through new facilities, acquisitions and expansions of existing operations.
During the quarter, AZZ began developing a galvanizing plant in the Tulsa area, supported by a major customer. The facility is expected to begin operations in the second half of fiscal 2028.
Sweeney noted that new galvanizing facilities typically require US$35-million to US$50-million of capital investment and can generate US$20-million to US$30-million in annual revenue.
AZZ is also expanding capacity at existing facilities in Texas, Kansas City and Reno, while evaluating another three to six projects requiring less than US$10-million each.
The company completed its US$57.5-million acquisition of Seattle Galvanizing during Q2, establishing a presence in the Pacific Northwest. Sweeney estimates the acquired facilities could generate US$35-million to US$40-million in combined annual revenue.
AZZ raised its fiscal 2027 guidance to revenue of US$1.825-billion to US$1.875-billion, Adjusted EBITDA of US$380-million to US$420-million and adjusted EPS of US$7.00 to US$7.30.
The company also increased planned capital spending to US$80-million to US$100-million to support capacity expansion and technology improvements.
AZZ ended Q2 with US$500-million of debt, down from US$515-million in the prior quarter, and net leverage of 1.3 times trailing-12-month Adjusted EBITDA.
Sweeney’s US$170.00 target is based on 13.7 times his fiscal 2027 Adjusted EBITDA estimate and 12.8 times his fiscal 2028 estimate.
He expects AZZ to generate Adjusted EBITDA of US$408.5-million on revenue of US$1.85-billion in fiscal 2027, improving to Adjusted EBITDA of US$436.7-million on revenue of US$1.96-billion in fiscal 2028.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.