Government contracts have derisked Volatus Aerospace, this analyst says

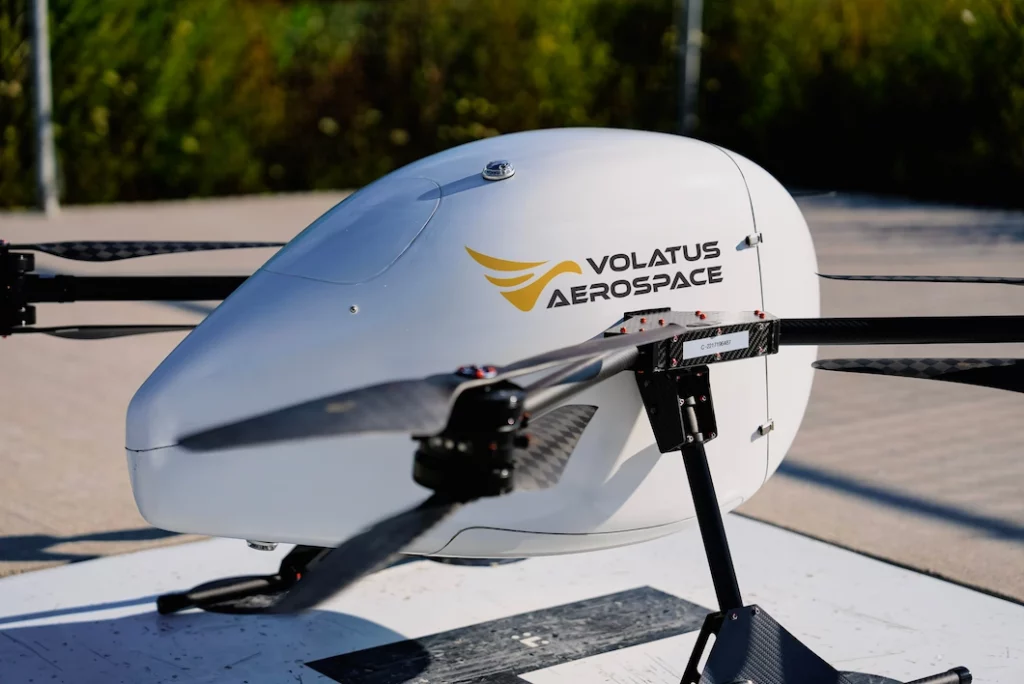
Haywood Securities analyst Gianluca Tucci says Volatus Aerospace’s (Volatus Aerospace Stock Quote, Chart, News, Analysts, Financials TSX:FLT) new Canadian defence contract reduces risk in the company’s defence growth thesis.
In a Sept. 10 update, Tucci reiterated his “Buy” rating on Volatus.
Volatus was awarded a five-year Government of Canada contract to supply low-cost tactical ISR uncrewed aircraft systems to the Canadian Armed Forces.
The initial order covers 100 systems, with Canada holding options to buy up to another 4,900 units. The framework is capped at $5,000 per unit, for a maximum value of $25-million.
“We view this contract as a significant de-risking event to our thesis which moves FLT to a real Canadian defence partner,” Tucci said.
The award follows Volatus’s qualification across all five streams of Canada’s Defence Drone Initiative Marketplace and marks its first Canadian Armed Forces contract under that program.
Initial deliveries are expected to begin in Q4 2026. The contract includes aircraft, payloads, ground control stations, data links, training, sustainment, spares and software support.
The quick conversion from marketplace qualification to contract win supports the view that Volatus could see more requests for quotes under Canada’s Defence Industrial Strategy.
The contract also supports the company’s domestic manufacturing thesis, with work tied to its Mirabel, Que., manufacturing hub and Vaughan, Ont., operations centre.
Defence remains the core of the Volatus investment thesis as the company scales toward becoming a sovereign aerospace and defence platform.
Volatus recently completed a $34.5-million bought deal financing, opened a 53,000-square-foot manufacturing and systems integration facility at Montreal-Mirabel airport and introduced its V-Cortex AI flight controller and autonomy operating system at CANSEC 2026.
Tucci expects Volatus to generate negative Adjusted EBITDA of $8.6-million on revenue of $40-million in fiscal 2026, improving to negative Adjusted EBITDA of $3.7-million on revenue of $65.2-million in fiscal 2027.
-30-
Tara Whittet
Writer
Tara Whittet is Senior Sales Manager at Cantech Letter.
Related Posts
Ventum analyst Rob Goff maintained his bullish view on Volatus Aerospace (Volatus Aerospace Stock Quote, Chart, News, Analysts, Financials TSXV:FLT)...
Ventum Capital Markets analyst Rob Goff maintained his “Buy” rating on Volatus Aerospace (Volatus Aerospace Stock Quote, Chart, News, Analysts,...