Alpha Teknova is a buy, this analyst says

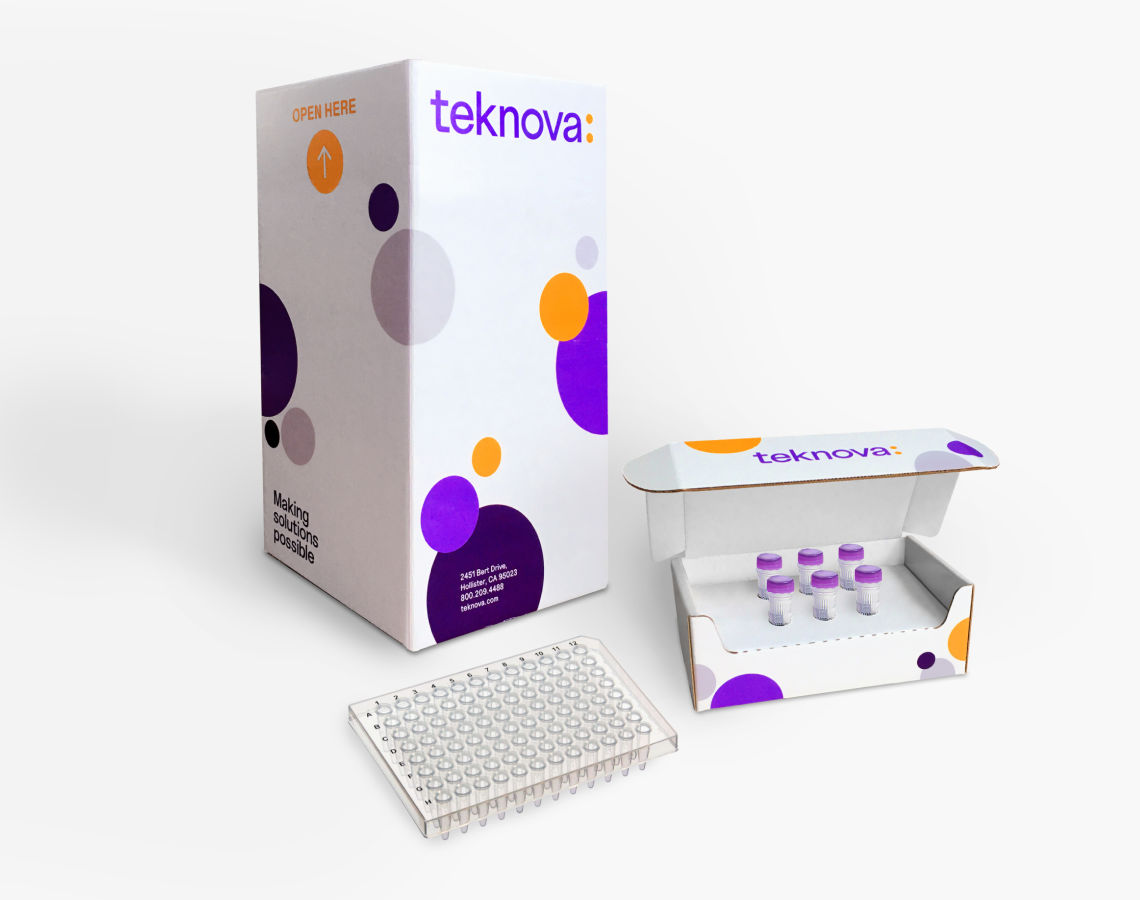
Roth Capital Partners analyst Max Masucci initiated coverage of Alpha Teknova (Alpha Teknova Stock Quote, Chart, News, Analysts, Financials NASDAQ:TKNO) with a “Buy” rating and US$ 7.00 target.
“With strong incremental gross margins, a recovering biotech/biopharma funding backdrop, and the advancement of its customers’ clinical solutions toward commercialization, we see a favorable 2026-2028 setup for top-line growth and progress towards breakeven,” Roth analyst Max Masucci said in an Aug. 5 report.
California-based Alpha Teknova produces reagents used in the discovery, development and commercialization of therapies, vaccines and molecular diagnostics. The company serves more than 3,300 customers across biotech, advanced therapies, life-sciences research tools and diagnostics, with customer retention above 95%.
Masucci said Alpha Teknova is differentiated by customizable products that support customer workflows from research-use-only applications to Good Manufacturing Practice-grade solutions, with fast turnaround times.
Its Lab Essentials segment supplies research-use-only catalogue and custom products, while Clinical Solutions supplies GMP-grade reagents used directly in customer diagnostics and therapeutics.
Masucci said Alpha Teknova supports about 70 customer therapy programs from preclinical through Phase 3, with spending expected to increase as programs advance toward launch.
The analyst said Clinical Solutions is the main growth driver. The segment grew 85% year-over-year in Q1 2026 to US$2.1-million, and Alpha Teknova expects at least one supported therapy or diagnostic to reach commercial approval by the end of 2027.
Masucci argued that the company should also benefit from a recovering biotech funding backdrop. Management saw a rebound in Q4 2025 that continued into Q1 2026, and Alpha Teknova has historically seen a four-quarter lag between funding changes and revenue trends.
Alpha Teknova has reduced its workforce by about 50% over the past three years and is increasing utilization at its modular, automated GMP-certified facility, which opened in 2023 and has US$200-million of revenue capacity.
Management expects about 70% of future revenue growth to flow to the bottom line. Masucci forecasts gross margin to expand to 42% in 2028 from 35% in 2026.
He expects Alpha Teknova to generate negative Adjusted EBITDA of US$6.7-million on revenue of US$40.5-million in fiscal 2025 and negative Adjusted EBITDA of US$8.5-million on revenue of US$43.8-million in fiscal 2026. He expects negative Adjusted EBITDA of US$4.3-million on revenue of US$51.0-million in fiscal 2027.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.