908 Devices is a buy, this analyst says

Roth Capital Partners analyst Max Masucci initiated coverage of 908 Devices (908 Devices Stock Quote, Chart, News, Analysts, Financials NASDAQ:MASS) with a “Buy” rating and US$11.00 target.
“We view MASS as a high-quality, pure-play handheld chemical detection company that provides exposure to attractive health, safety, and defence-tech growth markets,” Masucci said in his July 29 report.
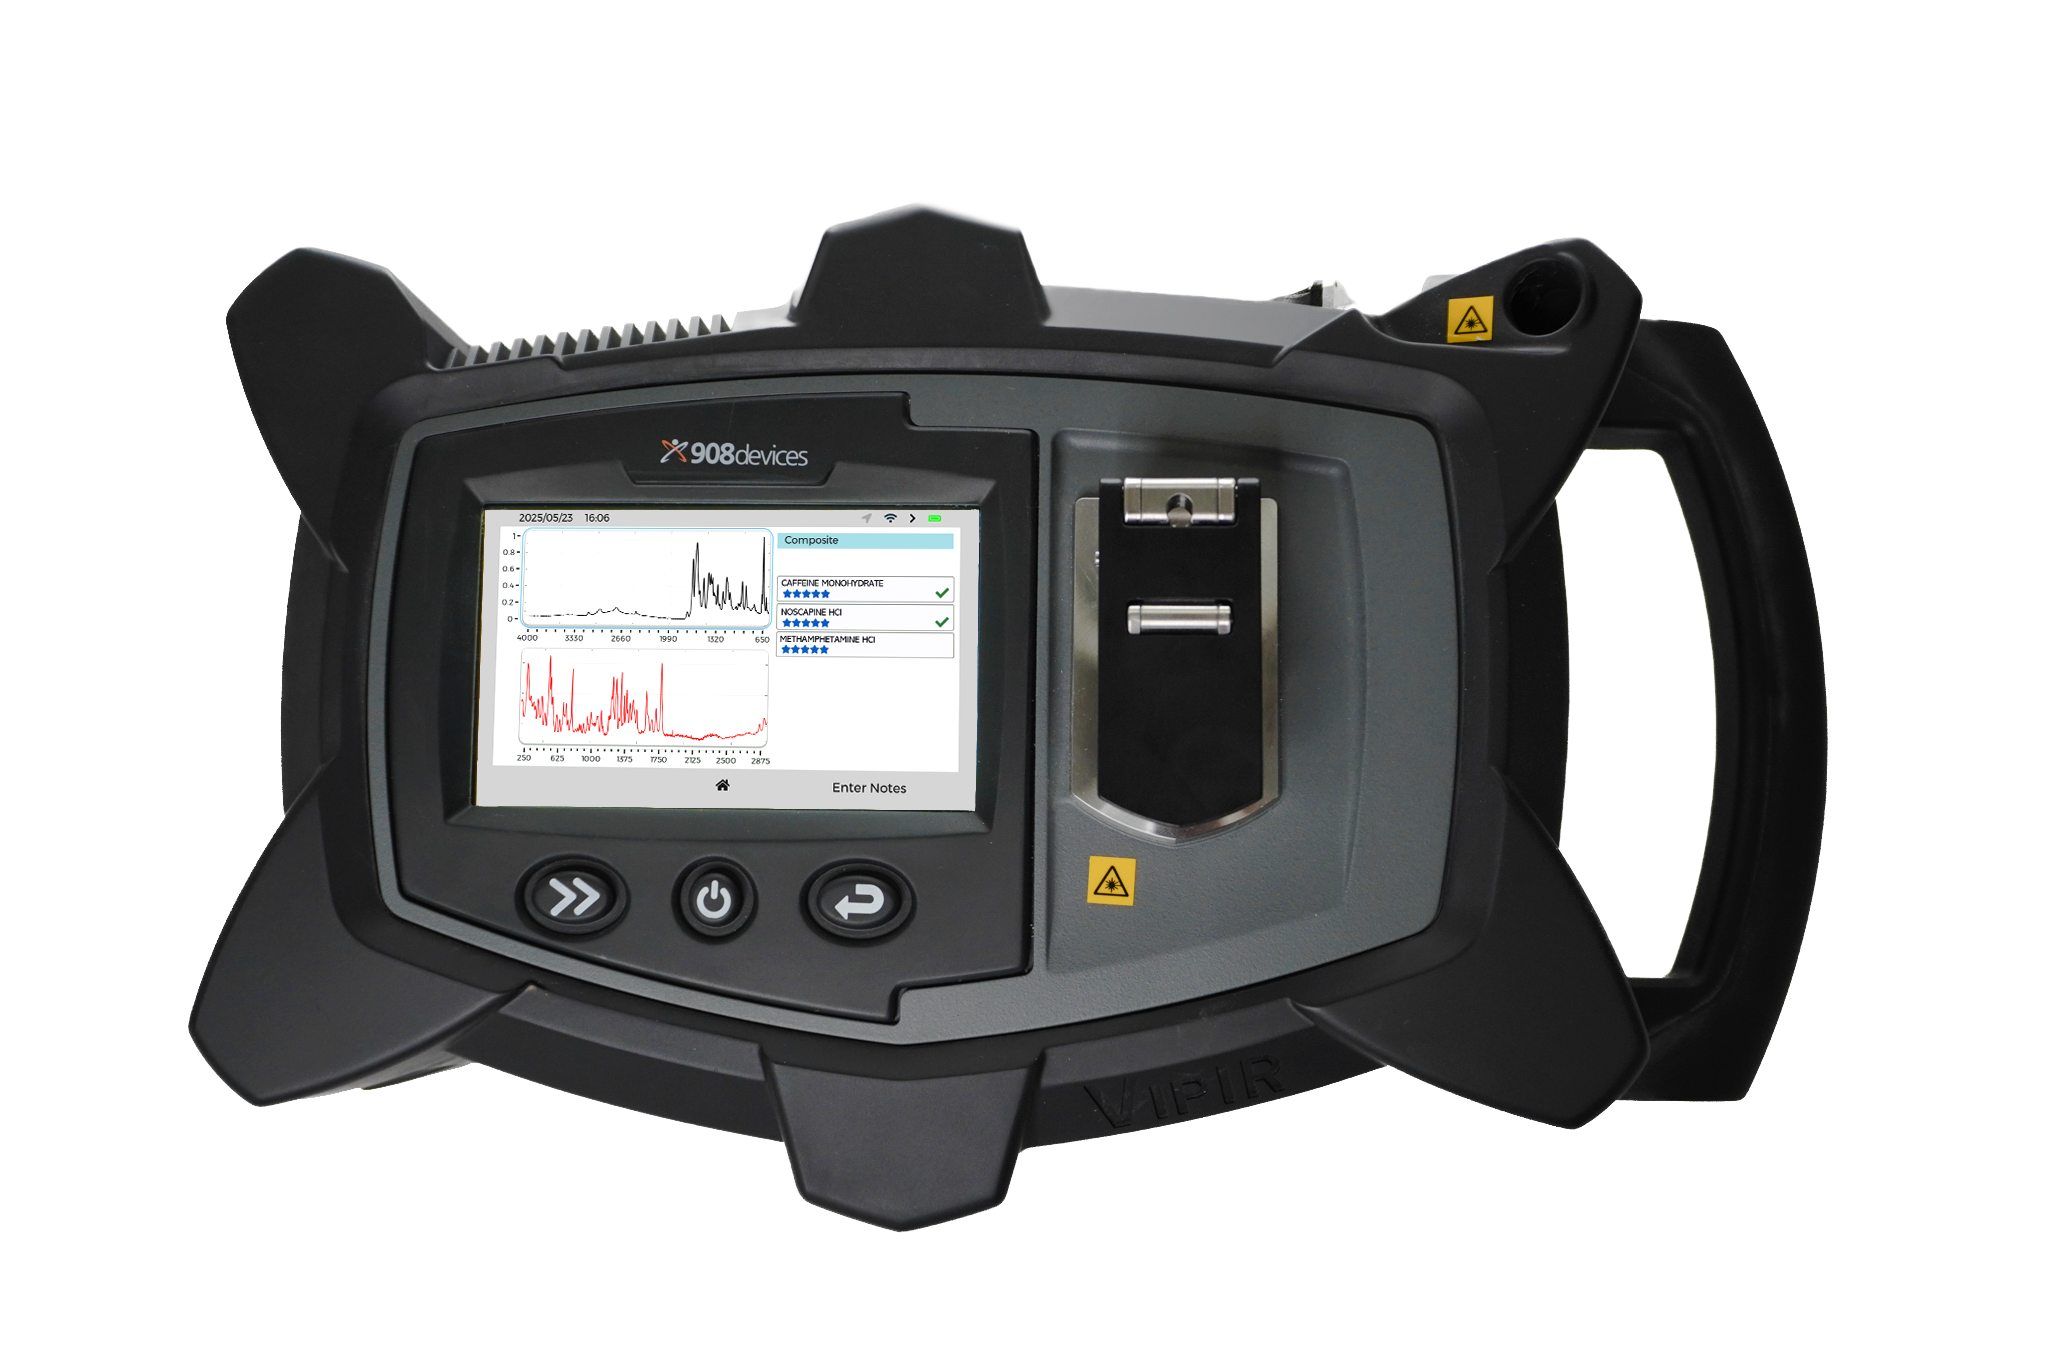
Based in Massachusetts, 908 sells handheld and portable devices that identify trace, bulk and airborne chemical threats. It serves more than 700 law enforcement, first responder and customs customers in more than 70 countries.
The company has more than 4,600 devices in the field against a placement opportunity of more than 20,000. Masucci sees an emerging recurring revenue opportunity and expects 908 to reach sustainable positive Adjusted EBITDA in the second half of 2027.
The analyst said management quality is central to the thesis, pointing to CEO Kevin Knopp’s role as co-founder of Ahura Scientific, which was acquired by Thermo Fisher in 2010, and board experience across life science tools, law enforcement and defence markets.
Masucci said the flagship MX908 device, with more than 3,100 units installed, is approaching a replacement cycle ahead of a simplified next-generation platform expected in 2026.
908’s FTIR portfolio remains the key near-term growth driver, while the recently acquired NIRLab platform expands the company into a narcotics screening market it estimates at US$200-million.
A potential full-rate production award for 908’s AVCAD program with the U.S. Department of Defense could add up to US$10-million of annual revenue for five to seven years, Masucci said. The opportunity is not included in his estimates or consensus forecasts.
He said the March 2025 sale of 908’s bioprocessing portfolio to Repligen removed about US$20-million of annual operating losses and sharpened the company’s focus on chemical detection, safety and defence markets.
Masucci said the stock trades at 2.7 times his 2027 revenue forecast, a 37% discount to small- and mid-cap tools and safety/defence peers. His US$11 target is based on 4.6 times EV/sales applied to his 2027 revenue forecast of US$80.5-million.
He expects 908 to generate negative Adjusted EBITDA of US$5.4-million on revenue of US$68.5-million in fiscal 2026, improving to negative Adjusted EBITDA of US$700,000 on revenue of US$80.5-million in fiscal 2027.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.