Blackline Safety shareholders should take the deal, this analyst says

Ventum Capital Markets analyst Amr Ezzat moved Blackline Safety (Blackline Safety Stock Quote, Chart, News, Analysts, Financials TSX:BLN) to “Tender” from “Buy” and raised his target to C$9.00 from C$8.25 after the company agreed to be acquired by Francisco Partners for C$9.00 a share in cash plus a contingent value right of up to C$0.50 a share tied to ARR targets.
On April 8, Ezzat said the deal represents a strong outcome for shareholders, particularly in a difficult small-cap technology market, with total consideration of up to C$9.50 a share implying a roughly 28% premium to the 20-day VWAP, or about 35% including the CVR.
“We view the transaction as a strong and well-timed outcome for shareholders, delivering an attractive premium and immediate liquidity, while retaining exposure to continued execution through the CVR structure,” he said.
He said the offer reflects Blackline’s steady operational progress, including durable ARR growth, strong net dollar retention and improving profitability and is consistent with the company’s transition toward a higher-quality recurring revenue model. At C$9.00 a share the valuation works out to about 4.4 times Ezzat’s fiscal 2026 revenue estimate and 30.7 times his fiscal 2027 EBITDA estimate, rising to 4.7 times and 32.4 times, respectively, if the CVR pays out in full.
Ezzat said the CVR gives shareholders some participation in future ARR growth, but he views it as contingent upside rather than core value. The structure pays nothing below $145-million in ARR and the full amount above about $149-million, which he said implies Blackline would need to deliver about a 33% ARR compound annual growth rate from October 2025 levels to achieve the full payout. Because the CVR is back-end loaded, non-transferable and pays only at maturity, he said it should be discounted versus its headline value.
He also pointed to the decision by about 31% of shareholders, including management and key strategic holders, to roll equity into the private company as a sign of confidence in Blackline’s longer-term growth profile. Combined with voting support agreements covering about 34% of shares outstanding, no financing condition and a credible buyer, Ezzat said deal completion risk appears low.
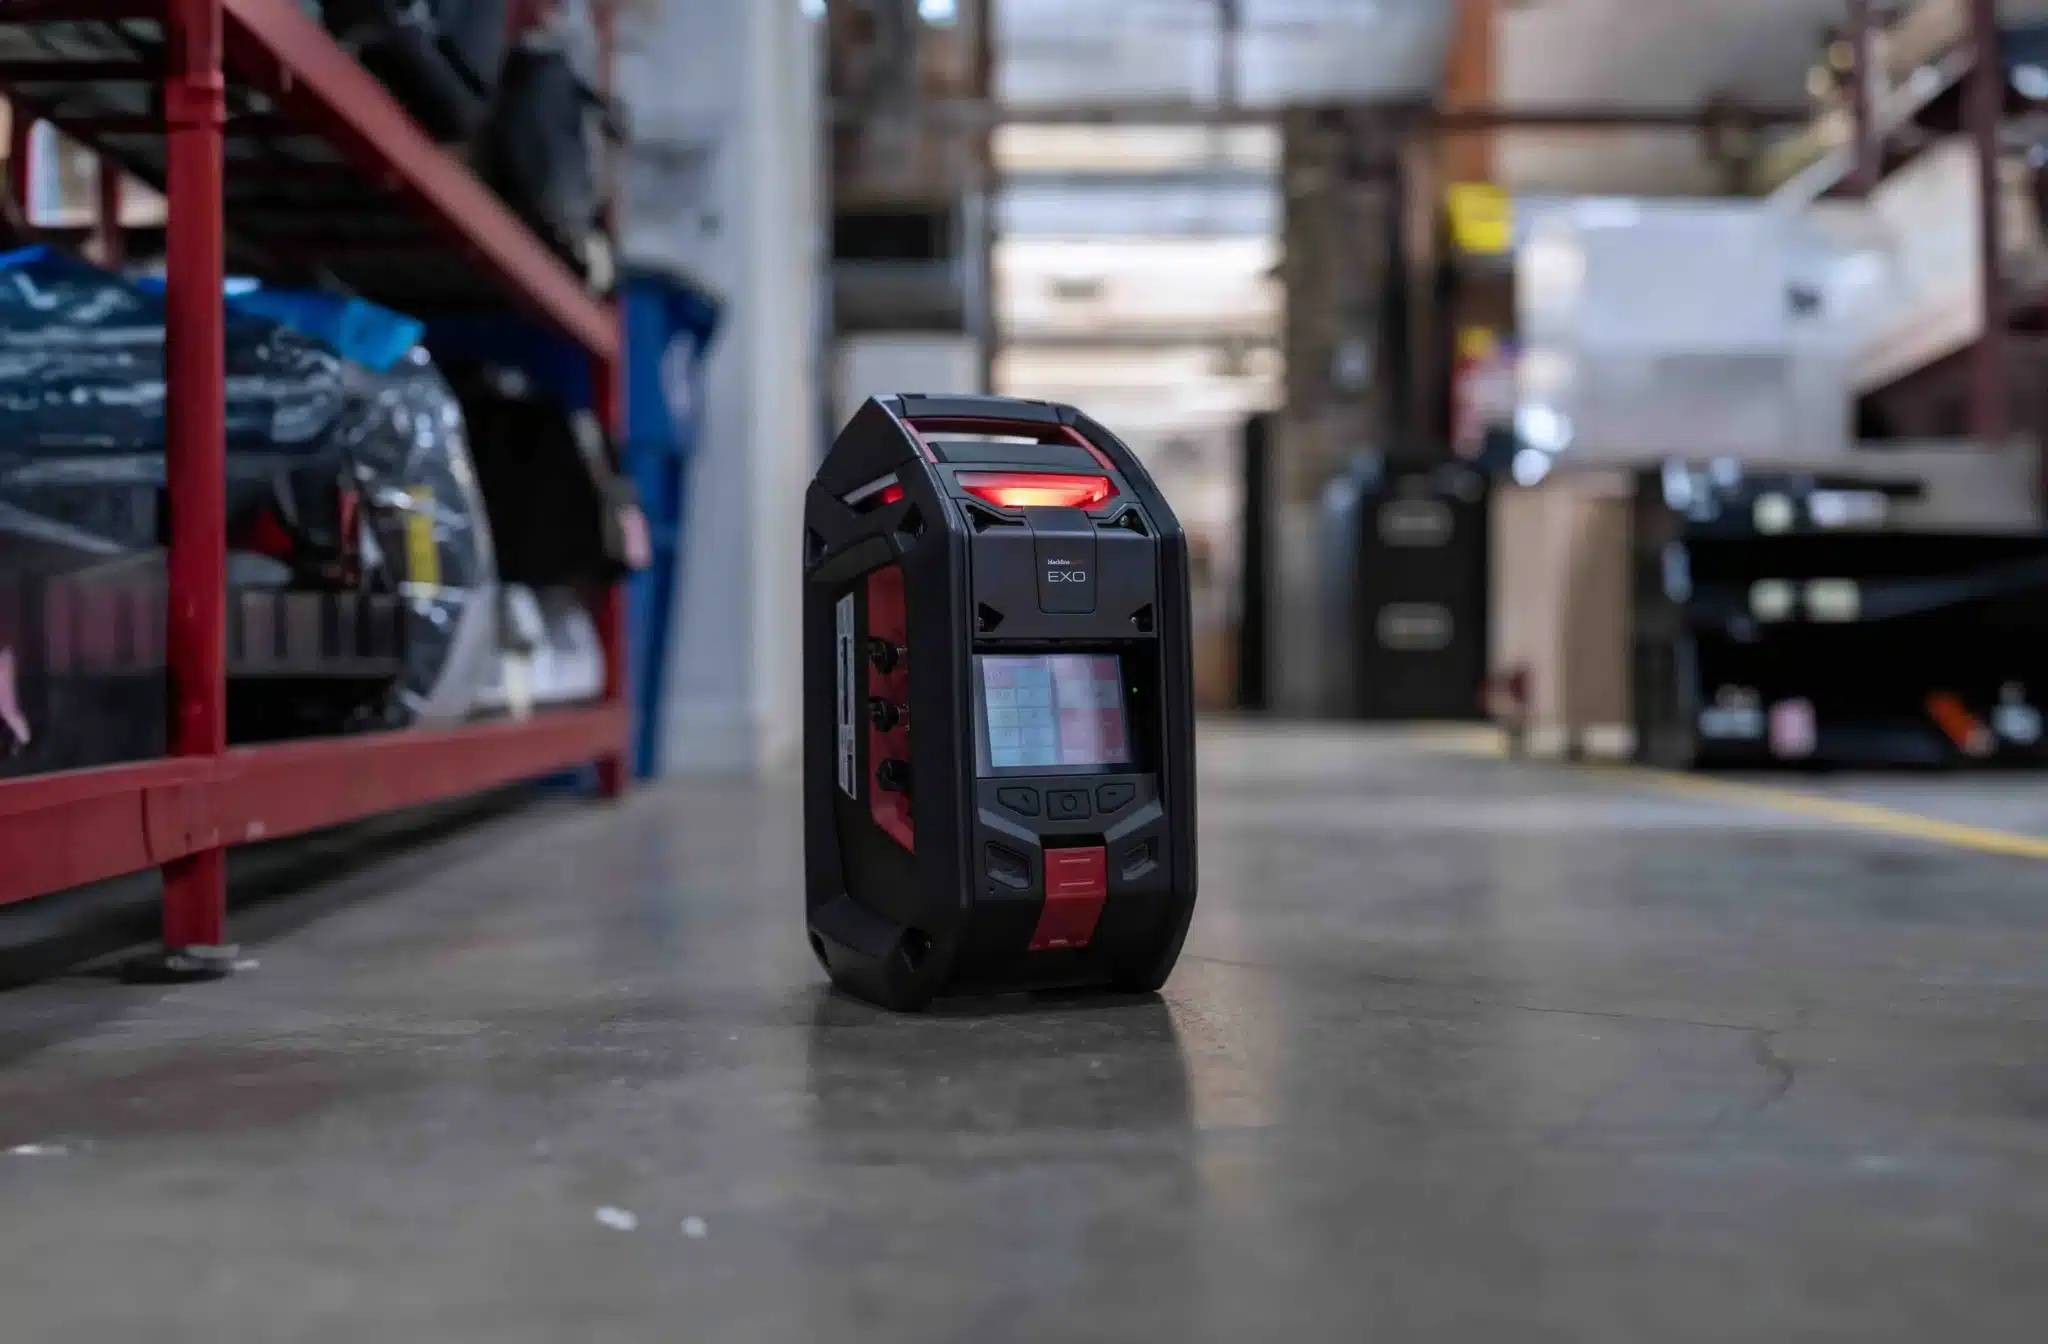
The analyst said the transaction fits with the broader evolution of the story, as Blackline has increasingly shifted toward a connected-worker platform where recurring services are the main driver of value.
He said Blackline should generate Adjusted EBITDA of $11.0-million on revenue of $170.2-million in fiscal 2026, improving to Adjusted EBITDA of $24.6-million on revenue of $204.2-million in fiscal 2027.
-30-
Tara Whittet
Writer
Tara Whittet is Senior Sales Manager at Cantech Letter.
Related Posts
Ventum Capital Markets analyst Amr Ezzat reiterated his “Buy” rating and C$8.25 price target on Blackline Safety (Blackline Safety Stock...
ATB Capital Markets said on Jan. 11 that it remains optimistic on Blackline Safety (Blackline Safety Stock Quote, Chart, News,...