Buy this Canadian space stock for a triple, analyst says

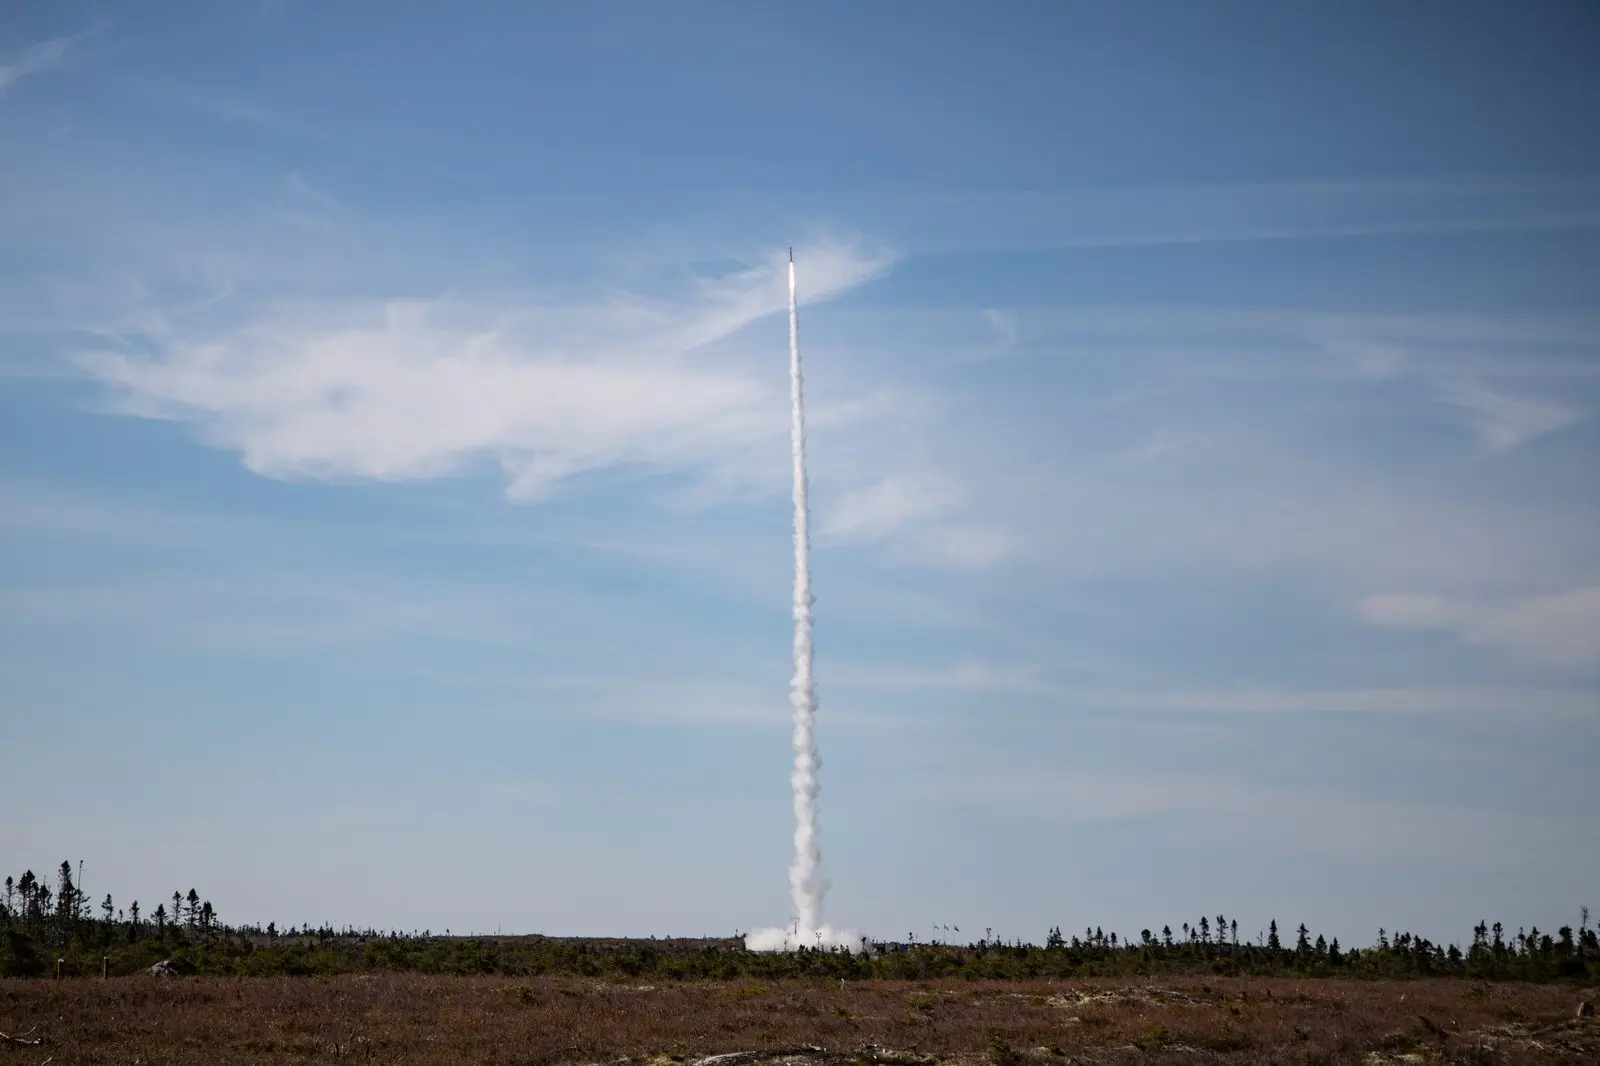
Beacon Securities analyst Russell Stanley maintained his “Buy” rating and $1.50 target on Maritime Launch Services (Maritime Launch Services Stock Quote, Chart, News, Analysts, Financials TSX:MAXQ), saying its graduation to the Toronto Stock Exchange could attract more investors as demand for satellite launch facilities increases.
Stanley said the Halifax-based company’s move from Cboe Canada to the TSX, effective Nov. 3, represents another milestone in the development of Spaceport Nova Scotia near Canso.
“We view this favourably, as it should broaden the investor audience for the stock,” Stanley said in his Nov. 2 report.
The analyst believes a growing shortage of launch capacity could increase demand for Maritime’s facilities, particularly as SpaceX transitions from its Falcon 9 rideshare program toward its larger Starship launch vehicle.
“Maritime is the only publicly traded pureplay on launch site access and we therefore expect additional interest as investors come to understand that bottleneck, and Spaceport Nova Scotia’s appeal,” he said.
The company is developing a spaceport designed to serve commercial satellite operators and government and defence customers. Stanley said Maritime has secured long-term agreements with two customers representing approximately $360-million in payments over 10 years.
Its next quarterly results, expected by mid-November, will be the first to reflect cash payments from both customers.
Following an initial US$3.75-million payment from Isar Aerospace in August, Stanley estimates Maritime is now receiving more than $10-million in quarterly cash payments. He said the contracted revenue provides greater visibility as the company advances construction and prepares its launch facilities for commercial operations.
Construction milestones, including the handover of Isar Aerospace’s dedicated launch pad, could provide additional catalysts. Two of the four launch pads planned for Spaceport Nova Scotia’s first phase are covered by long-term agreements, leaving room for additional customer contracts.
Maritime also has an agreement with Reaction Dynamics for one orbital launch attempt, which Stanley believes could lead to a longer-term relationship.
Stanley thinks the company’s location provides an advantage because its access to the Atlantic Ocean allows rockets to reach a broad range of orbital trajectories without flying over populated areas. The site is permitted for medium-class, two-stage rockets capable of delivering five tonnes to low-Earth orbit and could support more than 150 days of launch activity annually.
He also pointed to broader industry efforts to increase launch capacity. U.S. launch facilities supported 181 launches in 2025, with SpaceX accounting for 170, or approximately 94%. Stanley said U.S. government plans to support at least 1,000 annual launches by 2030 could create substantial demand for additional launch infrastructure.
“US based facilities represent known entities, but that pace of demand growth will outstrip capacity, necessitating additional launch sites,” he said.
Despite the growth outlook, Stanley believes Maritime’s valuation remains attractive. The shares trade at approximately nine times his fiscal 2027 Adjusted EBITDA forecast, compared with 77 times for a broad peer group. He expects that multiple to decline to four times estimated 2028 Adjusted EBITDA as the company’s contracted operations expand.
Stanley forecasts Maritime will generate Adjusted EBITDA of $9-million on revenue of $23-million in fiscal 2026, improving to $39-million on revenue of $73-million in fiscal 2027. For fiscal 2028, he expects Adjusted EBITDA of $87-million on revenue of $130-million.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts

Maritime Launch Services’ (Maritime Launch Services Stock Quote, Chart, News, Analysts, Financials CBOE:MAXQ) Q2 results showed the first meaningful revenue...
Beacon Securities analyst Russell Stanley says recent comments from U.S. Space Force leadership add support to his thesis that launch-site...