Verano Holdings remains undervalued, this analyst says

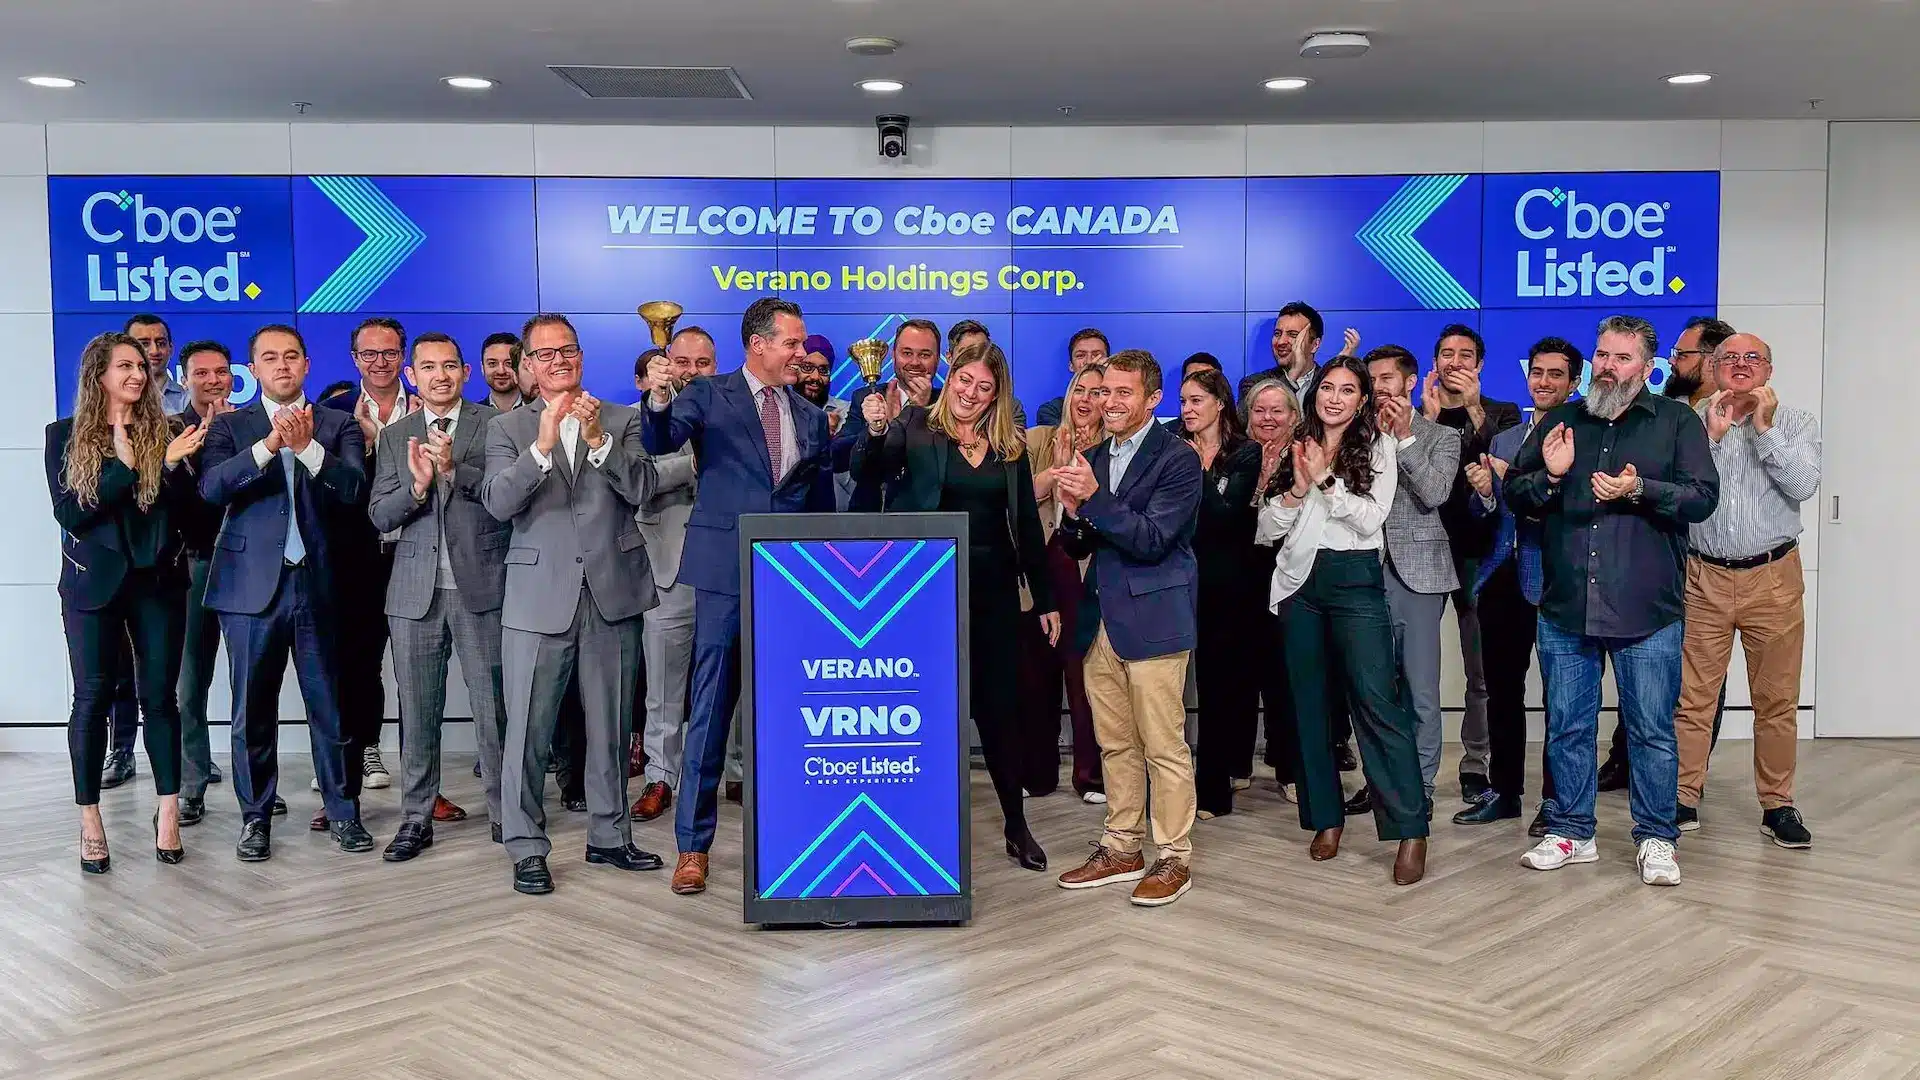
On Oct. 29, Haywood Securities analyst Neal Gilmer maintained his “Buy” rating and C$18.75 target on Verano Holdings (Verano Holdings Stock Quote, Chart, News, Analysts, Financials NEO:VRNO) following third-quarter results that fell short of expectations but showed improved margins and strong operating cash flow.
Gilmer argued that the U.S. cannabis producer remains positioned for growth as it expands its retail operations, invests in production efficiency and prepares for the anticipated launch of adult-use cannabis sales in Virginia in July 2027. “Verano is executing on its objectives and has runway for growth going forward with a focus on cash flow generation in 2026,” Gilmer said.
Verano reported Q3 revenue of US$212.4-million, up 4.7% year-over-year but below Haywood’s US$218.8-million estimate and consensus of US$216.1-million. Adjusted EBITDA was US$50.4-million, below Haywood’s US$55.6-million forecast and the Street’s US$52.1-million estimate. Gross margin improved to 47.1% from 45.8% in the previous quarter, while operating cash flow reached US$48.7-million.
Gilmer noted that management continues to invest in cultivation improvements and automation to support future margin growth. Verano raised its 2026 capital expenditure guidance to US$54-million to US$60-million from US$40-million to US$50-million.
Retail revenue increased 9% year-over-year, offsetting a 9.8% decline in wholesale revenue. “During the quarter, the Company opened one new dispensary in Florida, and subsequent to quarter end, Verano moved Zen Leaf Meriden to a new location and will relocate a dispensary in Pennsylvania tomorrow, bringing the total to 163 dispensaries nationwide,” Gilmer said.
The analyst expects the company’s retail expansion and potential acquisitions to support revenue growth across established and developing markets. “Verano has been progressing through its ambitious expansion plans since going public to drive revenue growth both in core markets as well as developing markets,” Gilmer said. “Furthermore, we believe the company will be opportunistic on the acquisition front to go deeper in its existing markets.”
Following the results, Gilmer reduced his fiscal 2026 revenue forecast to US$855.4-million from US$864.7-million and his Adjusted EBITDA estimate to US$207.5-million from US$215.9-million.
For fiscal 2027, he increased his revenue forecast to US$903.5-million from US$889-million, reflecting stronger anticipated growth in the second half of the year as Virginia introduces adult-use sales. However, he lowered his 2027 Adjusted EBITDA estimate to US$237.8-million from US$241.5-million.
Gilmer said Verano remains inexpensive relative to its competitors, trading at approximately 3.2 times estimated 2027 EV/Adjusted EBITDA, compared with 5.6 times for its U.S. Tier 1 peer group. “Verano remains undervalued within its peer group despite its strong operating metrics, expense management, and free cash flow,” he said.
His C$18.75 target is based on six times estimated fiscal 2027 EBITDA, discounted by 15%.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Haywood analyst Neal Gilmer maintained a “Buy” rating and $3.75 target on Verano Holdings (Verano Holdings Stock Quote, Chart, News,...
Russell Stanley of Beacon Securities maintained a “Buy” rating and C$5.00 price target on Verano Holdings (Verano Holdings Stock Quote,...