Neo Performance Materials is an “uncommon value”, this analyst says

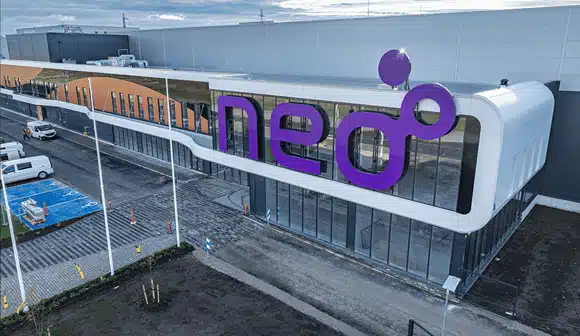
Neo Performance Materials’ (Neo Performance Materials Stock Quote, Chart, News, Analysts, Financials TSX:NEO) new partnership with Carester SAS strengthens the supply and recycling plan behind its NARVA magnet growth strategy, Paradigm Capital says.
Analyst J. Marvin Wolff reiterated his “Buy” rating and $50.70 target on Neo.
“We are of the view that the shares offer uncommon value at these levels and should benefit from a multiple expansion along with higher profitability as a strong participant in the EV growth curve,” Wolff said in an Aug. 31 update.
Neo announced a strategic partnership with Carester, a newly formed rare earth recycler and refiner based in Lacq, France.
Wolff said the agreement has three main parts: securing heavy rare earth supply for NARVA, giving Neo a channel to recycle NARVA production scrap and allowing Neo’s Silmet facility to process Carester’s mixed rare earth carbonate.
Carester is expected to initially recycle 2,000 tonnes per year of permanent magnets, producing neodymium-praseodymium, dysprosium and terbium. Wolff said that should help support NARVA’s heavy rare earth needs.
The agreement also allows Carester to recycle swarf, or metal cuttings, from NARVA’s sintered magnet production. Wolff said about 25% of the material from a magnetic block is typically cut away during production.
Silmet will process Carester’s mixed rare earth carbonate, with Neo retaining the light rare earths and Carester taking back the heavy rare earth component. Wolff said that should improve Silmet’s capacity utilization and broaden its supply chain.
The analyst said NARVA remains Neo’s key growth opportunity, serving electric vehicle, robotics and wind turbine markets. His sintered magnet rollout model assumes 2030 revenue of $450-million and EBITDA of $84-million from 5,600 net tonnes of magnets.
Wolff expects Neo to generate Adjusted EBITDA of $146.0-million on revenue of $671.7-million in fiscal 2026, declining to Adjusted EBITDA of $128.4-million on revenue of $648.5-million in fiscal 2027 as prices ease from current elevated levels.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Paradigm Capital analyst J. Marvin Wolff has raised his price target on Neo Performance Materials (Neo Performance Materials Stock Quote,...
Bruce Campbell, president and portfolio manager at Stonecastle Investment Management, says Neo Performance Materials (Neo Performance Materials Stock Quote, Chart,...