Is Cargojet (TSX:CJT) a buy right now?

Cargojet’s (Cargojet Stock Quote, Chart, News, Analysts, Financials TSX:CJT) stronger-than-expected third-quarter results and ability to maintain margins despite higher fuel and labour costs have strengthened its outlook heading into the peak shipping season, according to Beacon Securities analyst Donangelo Volpe.
Volpe maintained his “Buy” rating and $130.00 target on the Mississauga-based air cargo company on Nov. 13, raising his revenue and earnings forecasts for 2026 and 2027.
Cargojet reported third-quarter revenue of $287-million, up 30% year-over-year and ahead of Volpe’s $265-million estimate, consensus of $271-million and the highest analyst forecast of $284-million. Adjusted EBITDA increased 28% to $90-million, exceeding his $80-million estimate and consensus of $82-million. Adjusted earnings per share reached $1.21, compared with his $0.81 forecast and consensus of $0.85.
Volpe said the company’s profitability was particularly encouraging given significant increases in operating costs.
“Adj. EBITDA margin was 31.5% compared with our 30% estimate and 32% last year, which we view as an impressive result considering average fuel prices increased 58% y/y and the new pilot agreement was fully reflected in Q3,” he said.
Higher fuel costs, which are largely passed through to customers, reduced the Adjusted EBITDA margin by approximately 1.9 percentage points. Crew costs increased about 16% following implementation of the new pilot agreement. However, Volpe expects the company to benefit from changes to scheduling and operating practices that were not fully implemented when the pilot agreement was completed in late July.
“The company expects additional productivity benefits as scheduling changes and operating provisions are fully implemented, with improvement anticipated following into peak season and into 2027,” he said. “We believe the continued margin preservation despite the short-term headwinds provides evidence that growing emphasis on revenue quality, pricing discipline, network efficiency and asset utilization is taking effect and is a solid setup heading into 2027.”
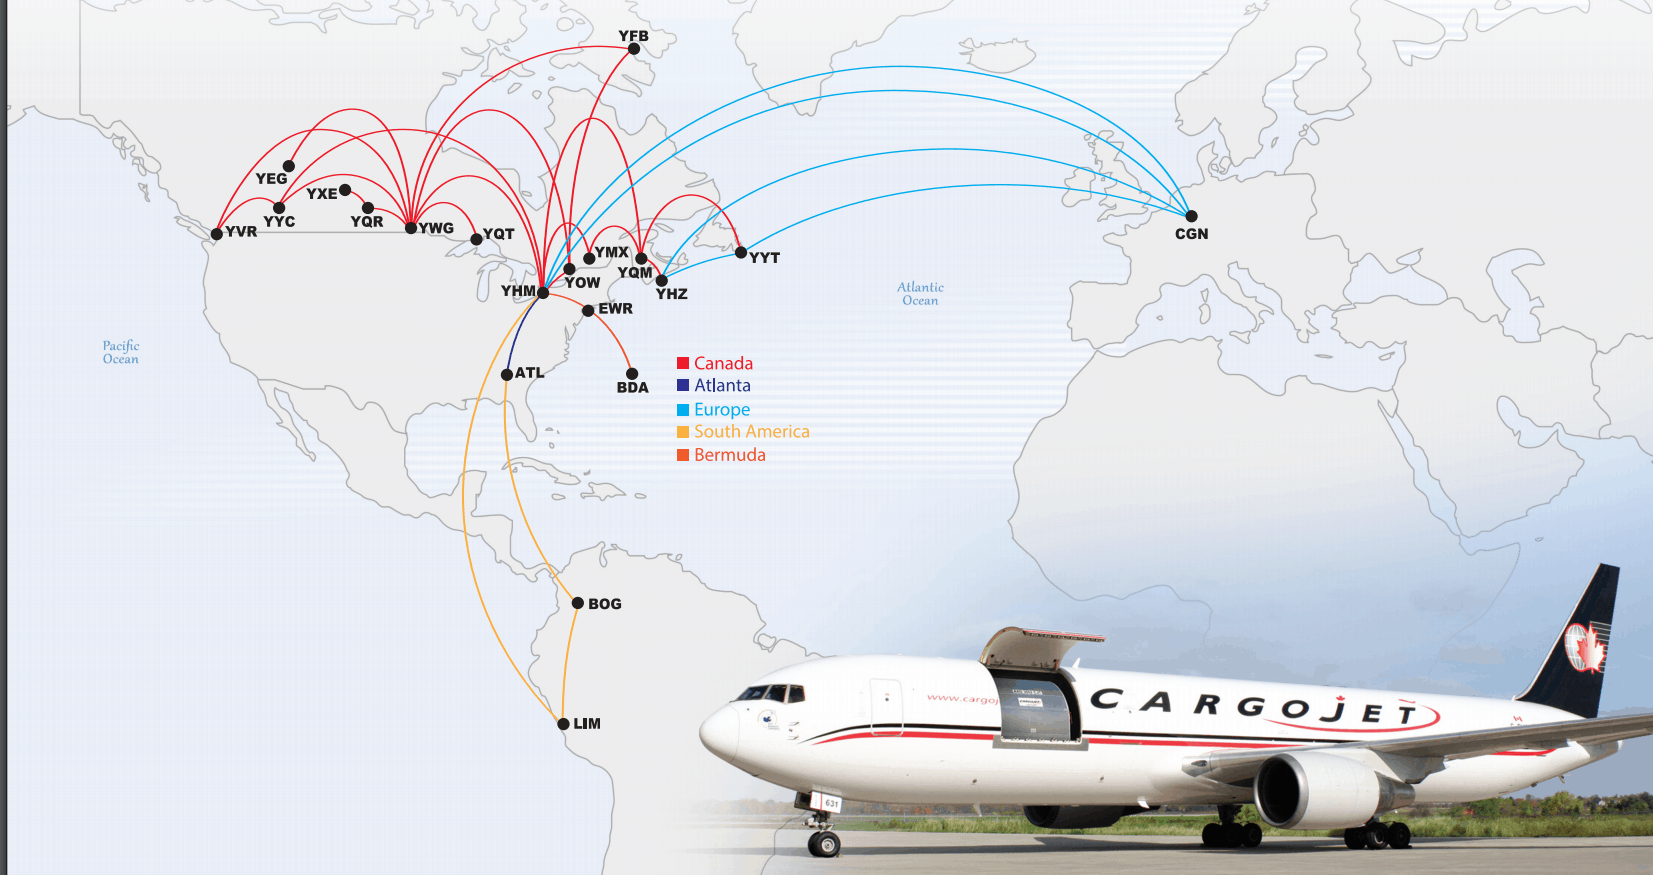
Cargojet reported domestic revenue, excluding fuel surcharges, of $106-million, up 6% year-over-year, supported by continued e-commerce growth. Revenue from aircraft, crew, maintenance and insurance (ACMI) services increased 11% to $61-million, reflecting increased flying requirements across several customers and improving global trade activity. Charter revenue rose 88% year-over-year to $62-million, supported by routes serving Europe, the Middle East and Latin America, along with additional flying for UPS.
Volpe thinks changes to Cargojet’s charter business could improve its longer-term financial performance. “Management also highlighted that charter is evolving from predominantly ad hoc flying toward a more balanced mix of scheduled and customer specific routes, which should provide greater revenue visibility and improve utilization of existing aircraft,” he said.
The company has also improved its cash flow and reduced leverage. Excluding proceeds from asset sales, Cargojet generated approximately $80-million in free cash flow during the first nine months of 2026, compared with an outflow of approximately $75-million a year earlier. Its net debt-to-Adjusted EBITDA ratio declined to 2.5 times from three times at the end of 2025.
Following the results, Volpe raised his fiscal 2026 revenue forecast to $1.122-billion from $1.085-billion and his Adjusted EBITDA estimate to $351-million from $340-million. His adjusted earnings-per-share forecast increased to $3.80 from $3.35. For fiscal 2027, he increased his revenue estimate to $1.167-billion from $1.13-billion, Adjusted EBITDA to $361.7-million from $350-million and adjusted earnings per share to $3.95 from $3.80.
The analyst noted that Cargojet trades at approximately 6.9 times expected Adjusted EBITDA over the next 12 months, below its five-year historical average of 7.5 times and 10-year average of 9.5 times.
He believes continued earnings growth and strong execution through the fourth quarter could narrow that valuation discount.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
TD Cowen analyst Tim James says Cargojet’s (Cargojet Stock Quote, Chart, News, Analysts, Financials TSX:CJT) valuation does not reflect the...
Paradigm Capital analyst Razi Hasan says Cargojet (Cargojet Stock Quote, Chart, News, Analysts, Financials TSX:CJT) has managed well through a...