Can you make money with Metatek-Group stock?

Metatek-Group’s (Metatek-Group Stock Quote, Chart, News, Analysts, Financials TSX:MTEK) strong sequential revenue growth and expectations for a further improvement in fourth-quarter earnings support a favourable outlook for the geophysical services company, according to Beacon Securities analyst Russell Stanley.
Stanley maintained his “Buy” rating and C$9.00 target on Nov. 12, saying increased utilization of the company’s survey systems and plans to expand its fleet could support substantial revenue and earnings growth.
“Earlier today, the company reported Q3 results that were short of headline consensus (revenue beat our street-low forecast),” Stanley said. “However, investors should focus on the strong q/q improvement in revenue/adj EBITDA, with the reiterated guidance pointing to further sequential growth of at least 17%/85% in Q4, featuring exceptional operating leverage.”
Metatek reported third-quarter revenue of US$9.7-million, up 29% year-over-year and 248% from the previous quarter. Revenue exceeded Stanley’s US$9.2-million forecast but fell short of consensus of US$10-million. The company generated Adjusted EBITDA of US$4.1-million, compared with a loss of US$1-million in the second quarter. Its Adjusted EBITDA margin reached 42%, compared with a negative 36% in the previous quarter. Higher utilization of Metatek’s two full tensor gravity (FTG) survey systems drove the improvement, including projects in Africa, Japan and Azerbaijan.
Gross margin increased to 64% from 36% in the previous quarter, while gross profit of US$6.2-million exceeded Stanley’s US$5.8-million estimate. However, increased operating expenses limited the earnings improvement.
“This was offset by higher-than-expected OPEX, with adj EBITDA coming slightly below our forecast ($4.1M v. $4.4M),” Stanley said.
Metatek reiterated its fiscal 2026 guidance for revenue of US$28-million to US$32-million and Adjusted EBITDA of US$11-million to US$13-million. According to Stanley, the guidance implies fourth-quarter revenue of at least US$11.4-million and Adjusted EBITDA of US$7.5-million, representing sequential increases of at least 17% and 85%, respectively.
The analyst said management expects operating expenses to remain relatively stable in the fourth quarter, allowing additional revenue to contribute more directly to earnings.
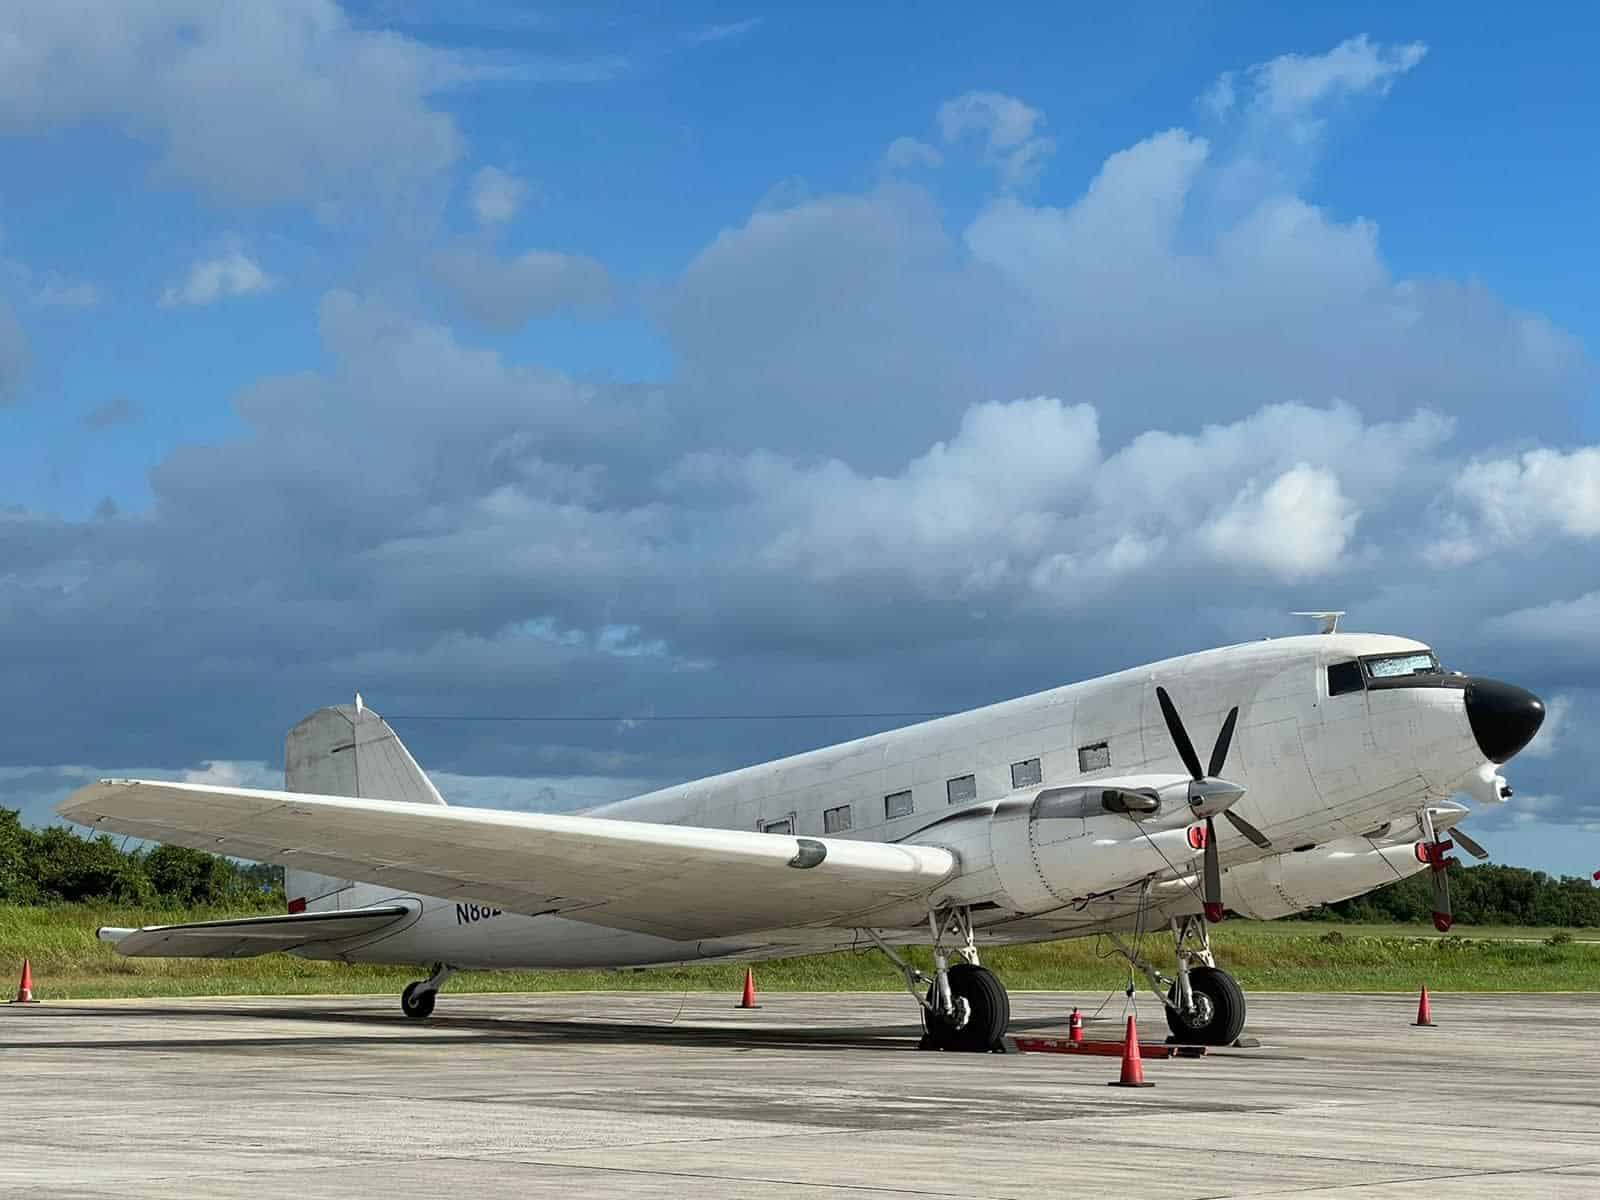
Metatek’s existing fleet is fully contracted through year-end, with expected contributions from work in Azerbaijan, West Africa and North Africa. The company’s longer-term growth strategy centres on increasing its fleet of FTG systems, which are used to produce detailed underground geological maps for mineral and resource exploration.
Metatek’s adjusted backlog declined from US$89-million in the previous quarter, although Stanley said the current fleet is approaching its practical capacity.
“During this morning’s conference call, management noted that an $80-$90M backlog is the effective maximum for the company’s current two-system fleet, as it represents ~2 years of work for each of the company’s FTG systems,” he said.
The company expects to add a third system, the refurbished Marine FTG, in early fiscal 2027. Following a planned paid testing program in the first quarter, Metatek could begin securing contracts for the additional capacity. It has also agreed to purchase a fourth system from Lockheed Martin, with delivery expected in fiscal 2029, and management expects to exercise an option to purchase a fifth system in early 2027. Stanley said the expansion could allow Metatek to pursue contracts beyond the capacity of its existing equipment.
MTEK has also reached an agreement with Bridger Aerospace to provide aviation services, with the first of three aircraft expected in mid-2027. The newer aircraft will be equipped to operate in Arctic conditions, potentially allowing Metatek to pursue work in regions such as Canada and Alaska that its existing aircraft cannot support.
Stanley forecasts fiscal 2026 revenue of US$30-million, down slightly from his previous estimate of US$30.3-million, while maintaining his Adjusted EBITDA forecast of US$11-million. For fiscal 2027, he reduced his revenue forecast to US$52-million from US$54.2-million to reflect the expected timing of the Marine FTG rollout, but increased his Adjusted EBITDA estimate to US$23.9-million from US$23.5-million. His fiscal 2028 forecast calls for revenue of US$70-million and Adjusted EBITDA of US$33.6-million, compared with his previous EBITDA estimate of US$32.3-million.
The analyst noted that Metatek trades at approximately 4.2 times his estimated fiscal 2027 Adjusted EBITDA, with additional contract wins, fleet expansion and fourth-quarter results expected in March among the potential catalysts for the stock.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts

Beacon Securities analyst Russell Stanley notes that Metatek Group (Metatek-Group Stock Quote, Chart, News, Analysts, Financials TSX:MTEK) has started work...
Beacon Securities analyst Russell Stanley says Metatek Group (Metatek-Group Stock Quote, Chart, News, Analysts, Financials TSX:MTEK) could be particularly catalyst-rich...