Analyst slashes target price on Ballard Power

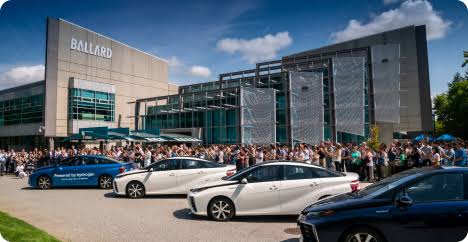
National Bank Financial analyst Baltej Sidhu lowered his target for Ballard Power Systems (Ballard Power Systems Stock Quote, Chart, News, Analysts, Financials, NASDAQ:BLDP) to US$3.00 from US$4.50 on Nov. 17 following weaker-than-expected third-quarter results, although improving margins and the acquisition of GeoPura could strengthen the company’s longer-term growth prospects.
Sidhu maintained his “Sector Perform” rating on the Vancouver-based hydrogen fuel cell manufacturer. His revised target is below the average analyst target of US$3.32.
“BLDP continues to execute, with greater margins, improving backlog and the GeoPura platform enhancing its growth profile,” Sidhu said. “Execution consistency is the key barometer, that will require repeatability to de-risk visibility for its stated targets. On account of estimate revisions, we lower our target.”
Sidhu said the company’s improving operating performance and expanded business model are encouraging, but sustained execution will be necessary to demonstrate that Ballard can achieve its profitability targets.
Ballard reported third-quarter revenue of US$22.5-million, down 31% from US$32.5-million a year earlier. Equipment sales and services contributed US$21.6-million, while energy sales and services generated US$900,000. Despite lower revenue, gross margin improved to 20% from 15%, reflecting pricing discipline, lower manufacturing costs and inventory adjustments. The company’s Adjusted EBITDA loss narrowed to US$12.4-million from US$31.2-million, while operating expenses declined 20% to US$28-million. Ballard reported a net loss from continuing operations of US$21.1-million, or US$0.07 per share, compared with US$28.1-million, or US$0.09 per share, a year earlier.
The company completed its acquisition of GeoPura on Aug. 28, expanding beyond fuel cell equipment into hydrogen production, distribution and power rentals. Management expects the combined business to generate higher-margin recurring revenue through its Energy-as-a-Service offering, which provides customers with hydrogen-powered electricity through rented hydrogen power units.
Following the acquisition, Ballard is targeting positive Adjusted EBITDA in the fourth quarter of 2027 and for the full year in 2028, supported by an approximately 30% compound annual revenue growth target over 2027 and 2028.
The company also reported an order backlog of US$180.6-million at the end of September, up 15% from the previous quarter. However, its 12-month order book declined 17% to US$61.4-million, partly reflecting the elimination of intercompany orders following the GeoPura acquisition.
Ballard increased its fiscal 2026 operating expense guidance to between US$90-million and US$100-million from US$65-million to US$75-million, including approximately US$12-million in integration costs.
It also raised its capital expenditure guidance to between US$10-million and US$13-million from US$5-million to US$10-million, including approximately US$10-million for expansion of its hydrogen power unit fleet.
Cash used in operating activities increased to US$35.4-million from US$22.9-million a year earlier, including US$6.8-million in acquisition-related costs. Ballard ended September with US$373.9-million in cash and equivalents, compared with US$525.7-million a year earlier.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
National Bank Financial analyst Baltej Sidhu says Ballard Power Systems (Ballard Power Systems Stock Quote, Chart, News, Analysts, Financials NASDAQ:BLDP)...
Ballard Power’s (Ballard Power Stock Quote, Chart, News, Analysts, Financials NASDAQ:BLDP) disappointing Q1 2025 results prompted Roth Capital Partners analyst...