ADF Group is a buy, this analyst says

Ventum Capital Markets analyst Daniel Lavoie says ADF Group’s (ADF Group Stock Quote, Chart, News, Analysts, Financials TSX:DRX) backlog is more durable than in the past, giving the company better revenue visibility.
In a Sept. 28 report, Lavoie launched coverage of ADF with a “Buy” rating and $20.50 target.
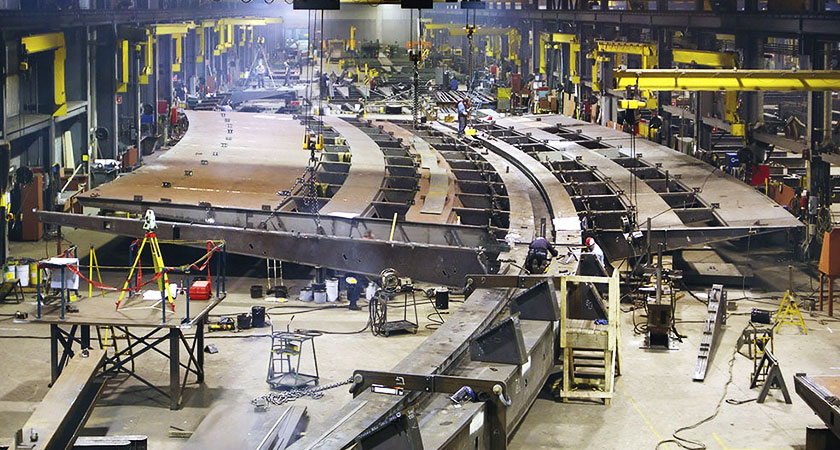
ADF designs, fabricates and installs large and complex structural steel components for non-residential construction markets. Its end markets include transportation infrastructure, airports, industrial facilities, commercial and institutional buildings and, following its acquisition of Groupe LAR, hydroelectric infrastructure.
“The key change in the ADF story, in our view, is not simply the size of the backlog, but its duration and composition,” Lavoie said.
The analyst said multi-year contracts now provide visibility several years forward, while the Canadian share of backlog has increased substantially.
Lavoie said that should reduce historical volatility in ADF’s project-based business and improve visibility around production, labour needs and capital spending.
He said investments in automation at ADF’s Terrebonne facility have structurally improved productivity and margins in the core business.
Lavoie also said the Groupe LAR acquisition adds a new growth platform, expanding ADF into machining, welding, industrial mechanics and large-scale hydroelectric infrastructure.
LAR’s backlog has grown to $243.3-million from $104.5-million before the acquisition, up 133% in roughly one year.
Lavoie said that growth is important because ADF had originally targeted increasing LAR’s backlog to more than $200-million within 18 months, a threshold reached well ahead of schedule.
The analyst argued that the pace of new awards suggests LAR’s main constraint is increasingly capacity rather than demand.
ADF is investing to expand capacity and modernize LAR’s Métabetchouan facility, with benefits expected to become more meaningful beginning in fiscal 2028.
Lavoie said ADF trades at about four times his fiscal 2028 EV/EBITDA estimate and 7.6 times earnings, which he views as attractive relative to the company’s earnings and cash generation potential.
“This balance sheet capacity should give ADF ample room to pursue additional industry consolidation, invest in organic growth opportunities, or return excess capital to shareholders through further share repurchases or dividends,” Lavoie said.
His $20.50 target is based on 6.0 times fiscal 2028 EV/EBITDA and 12.0 times earnings.
Lavoie expects ADF to generate Adjusted EBITDA of $48-million on revenue of $364-million in fiscal 2027, improving to Adjusted EBITDA of $79-million on revenue of $460-million in fiscal 2028.
-30-
Nick Waddell
Founder of Cantech Letter
Cantech Letter founder and editor Nick Waddell has lived in five Canadian provinces and is proud of his country's often overlooked contributions to the world of science and technology. Waddell takes a regular shift on the Canadian media circuit, making appearances on CTV, CBC and BNN, and contributing to publications such as Canadian Business and Business Insider.