Rapid Micro Biosystems has a 240% upside, this analyst says

Roth Capital Partners analyst Max Masucci says Rapid Micro Biosystems (Rapid Micro Biosystems Stock Quote, Chart, News, Analysts, Financials NASDAQ:RPID) offers exposure to automation in pharmaceutical microbial quality control.
In a recent report, Masucci launched coverage of Rapid Micro with a “Buy” rating and US$3.00 target.
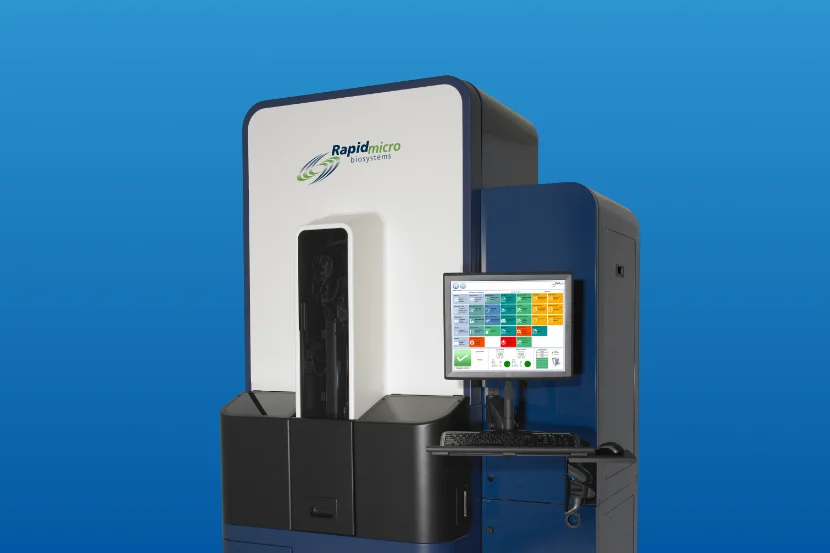
Rapid Micro’s Growth Direct platform automates microbial quality control, reducing a manual 15-step process to two steps and delivering results in about half the time.
Masucci said the company has placed about 200 Growth Direct systems across more than 100 sites, with customers including 75% of the top 20 global pharmaceutical companies and 86% of approved CAR-T manufacturers.
He said the installed base represents only about 2% of the roughly 10,000-system core pharmaceutical opportunity.
“We see a favourable setup supported by MilliporeSigma, consumable utilization, industry automation, and new biomanufacturing capacity, balanced against liquidity and execution risk,” Masucci said.
The company ended Q2 2026 with 169 validated systems, each adding consumable and service revenue.
Masucci said Rapid Micro is an installed-base expansion and margin inflection story.
Recurring revenue exceeded 60% of Q2 sales and rose 14% year-over-year, while consumables grew more than 20%.
Rapid Micro completed nine validations in Q2 and is guiding to at least 27 in 2026.
Gross margin improved to 15% in Q2, up from 4% a year earlier and negative 50% in 2022. Management is targeting mid- to high-20% gross margins exiting 2026 and more than 50% exiting 2028.
Masucci argued that the MilliporeSigma partnership should support placements, margins and strategic value.
“Its global reach should expand RPID’s funnel across customers, sites, geographies, and adjacent markets without proportional commercial investment,” he said.
The analyst also believes U.S. reshoring and new biomanufacturing capacity could provide a growth tailwind beginning in 2027, with greenfield facilities able to design Growth Direct into validation plans.
Rapid Micro ended Q2 with about US$20-million in cash and US$20-million in term debt.
Masucci’s US$3.00 target applies a 3.7 times EV/sales multiple to his 2027 revenue estimate of US$45.6-million and incorporates a US$20-million raise in Q2 2027.
Masucci expects Rapid Micro to generate negative Adjusted EBITDA of US$36.6-million on revenue of US$39.1-million in fiscal 2026, improving to negative Adjusted EBITDA of US$24.3-million on revenue of US$45.6-million in fiscal 2027.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.