
Be an “opportunistic buyer” of Plug Power, this analyst says


Roth Capital Partners says Plug Power’s (Plug Power Stock Quote, Chart, News, Analysts, Financials NASDAQ:PLUG) Q2 results showed improving margins, better revenue traction and a clearer path toward operating breakeven.
In an Aug. 12 update, analyst Craig Irwin reiterated his “Buy” rating on Plug and raised his target to US$5.00 from US$3.50.
“We would be opportunistic buyers at current levels for improving margins and revenue traction that raise visibility for operating breakeven, possibly as soon as during 2027,” Irwin said.
Plug reported Q2 revenue of US$178.3-million, ahead of Irwin’s US$165.0-million estimate and consensus at US$169.1-million. Adjusted EBITDA was negative US$64.0-million, better than consensus for negative US$73.0-million but below Irwin’s forecast for negative US$55.7-million.
Gross margin improved to negative 0.9%, compared with negative 13.2% in Q1 and negative 30.7% a year earlier. Irwin said the improvement was supported by positive equipment and service margins, better fuel margins and lower power purchase agreement losses.
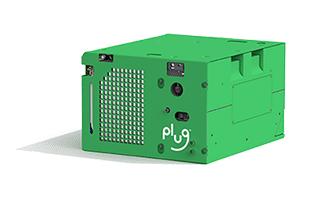
Plug deployed 1,666 GenDrive units in Q2, more than double the 739 units deployed a year earlier. Service revenue rose to US$29.8-million from US$16.4-million a year earlier, with two major customers planning to refurbish more than 20,000 units over the next three years.
Irwin said Plug is also seeing traction in electrolyzers, including progress on projects in the U.K., Quebec, Spain and Portugal.
Green hydrogen revenue increased 15% year-over-year to US$39.5-million, while fuel gross margin improved to negative 48% from negative 91% a year earlier as plant optimization and network utilization improved.
Plug also reduced its cash use to US$61-million in Q2, down 58% sequentially. Irwin said asset sales and cash released from power purchase agreements provide visibility for Q4 cash to exceed year-earlier levels.
The company now expects US$275-million of cash from asset monetization, up from its previous expectation of US$250-million.
Management raised its 2026 revenue growth guidance to 15% to 16% from 13% to 15%, citing a strong first half and better visibility for the second half. It also continues to target positive Adjusted EBITDA in Q4.
Irwin expects Plug to generate negative Adjusted EBITDA of US$213.4-million on revenue of US$815.0-million in fiscal 2026, improving to negative Adjusted EBITDA of US$150.0-million on revenue of US$895.0-million in fiscal 2027.
-30-
Rod Weatherbie
Writer
Rod Weatherbie is a journalist based in Prince Edward Island. Since 2004, he has written extensively about the Canadian property and casualty insurance landscape. He was also a founder and contributing editor for a Toronto-based arts website and a PEI-based food magazine. His fiction and poetry have been featured in The Fiddlehead, The Antigonish Review, and Juniper.
Related Posts
Plug Power’s (Plug Power Stock Quote, Chart, News, Analysts, Financials NASDAQ:PLUG) third-quarter revenue exceeded expectations as demand for hydrogen fuel-cell...

Roth Capital Markets analyst Craig Irwin reiterated his “Buy” rating and $3.50 12-month price target on Plug Power (Plug Power...